
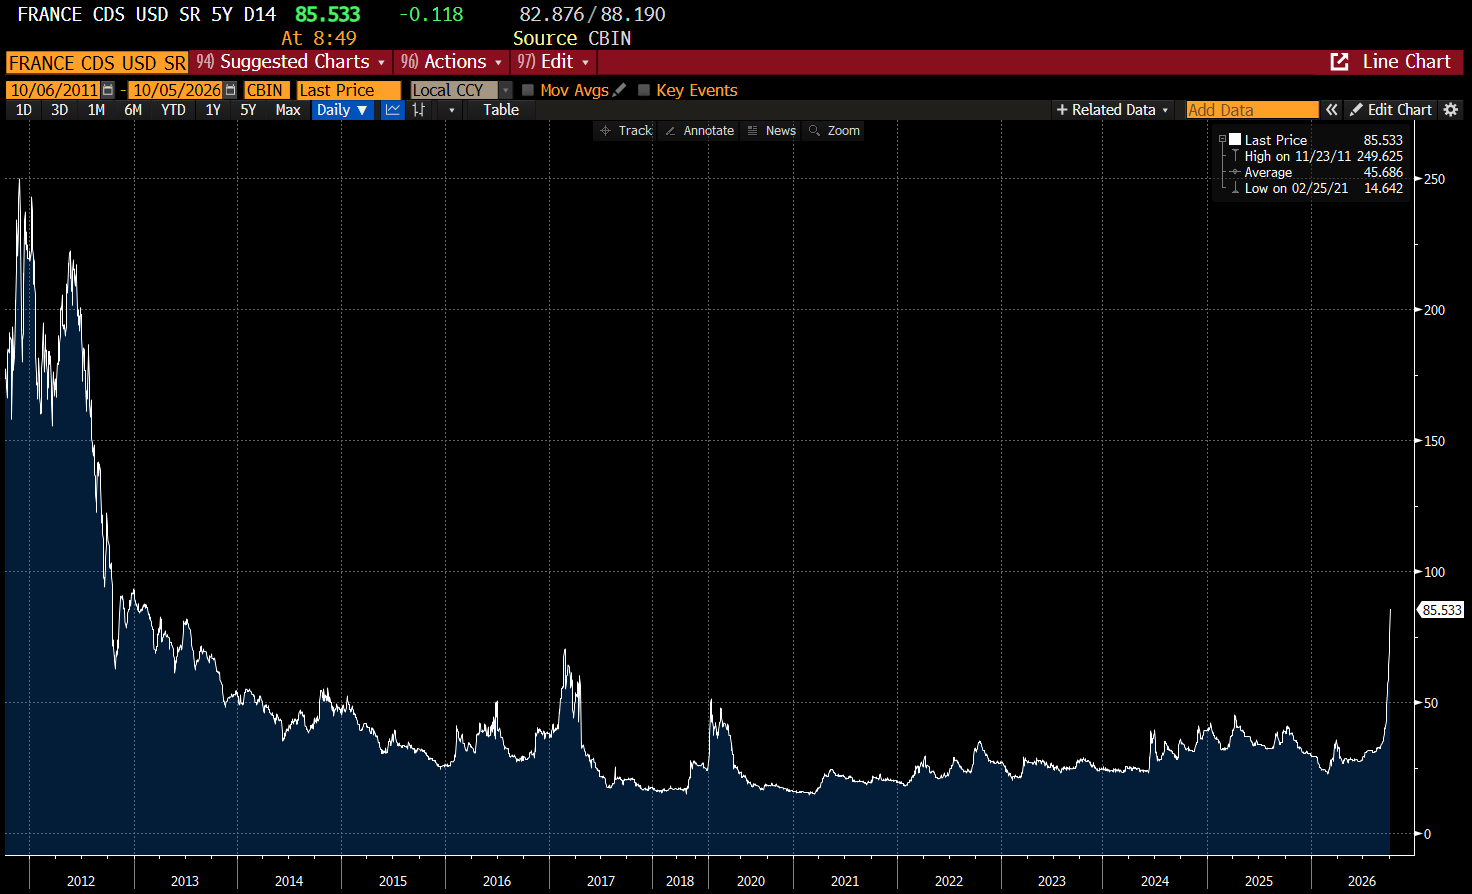
In case you have been living under a rock, French bonds have been under pressure. Typically, sovereign bonds cannot default, but with European bonds there is a risk that you are forced to leave Eurozone, so with European bonds, CDS can actually work as an indicator. French CDS have soared in recent weeks.
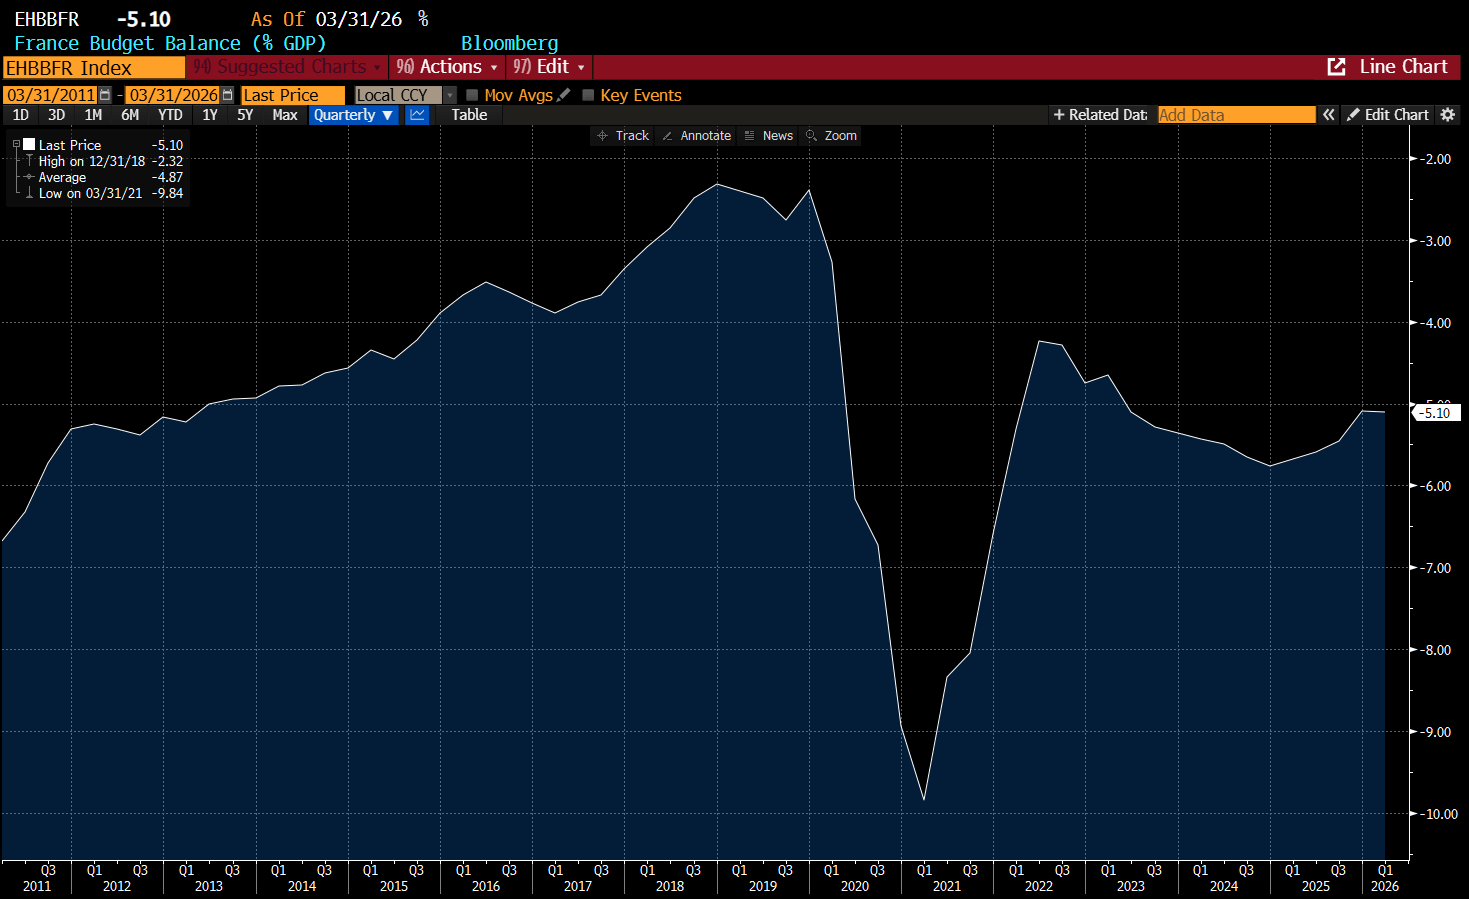
France has a lot of debt - but so do most countries. But it does have a budget deficit that is very high by European standards. 3% is the supposed limit.
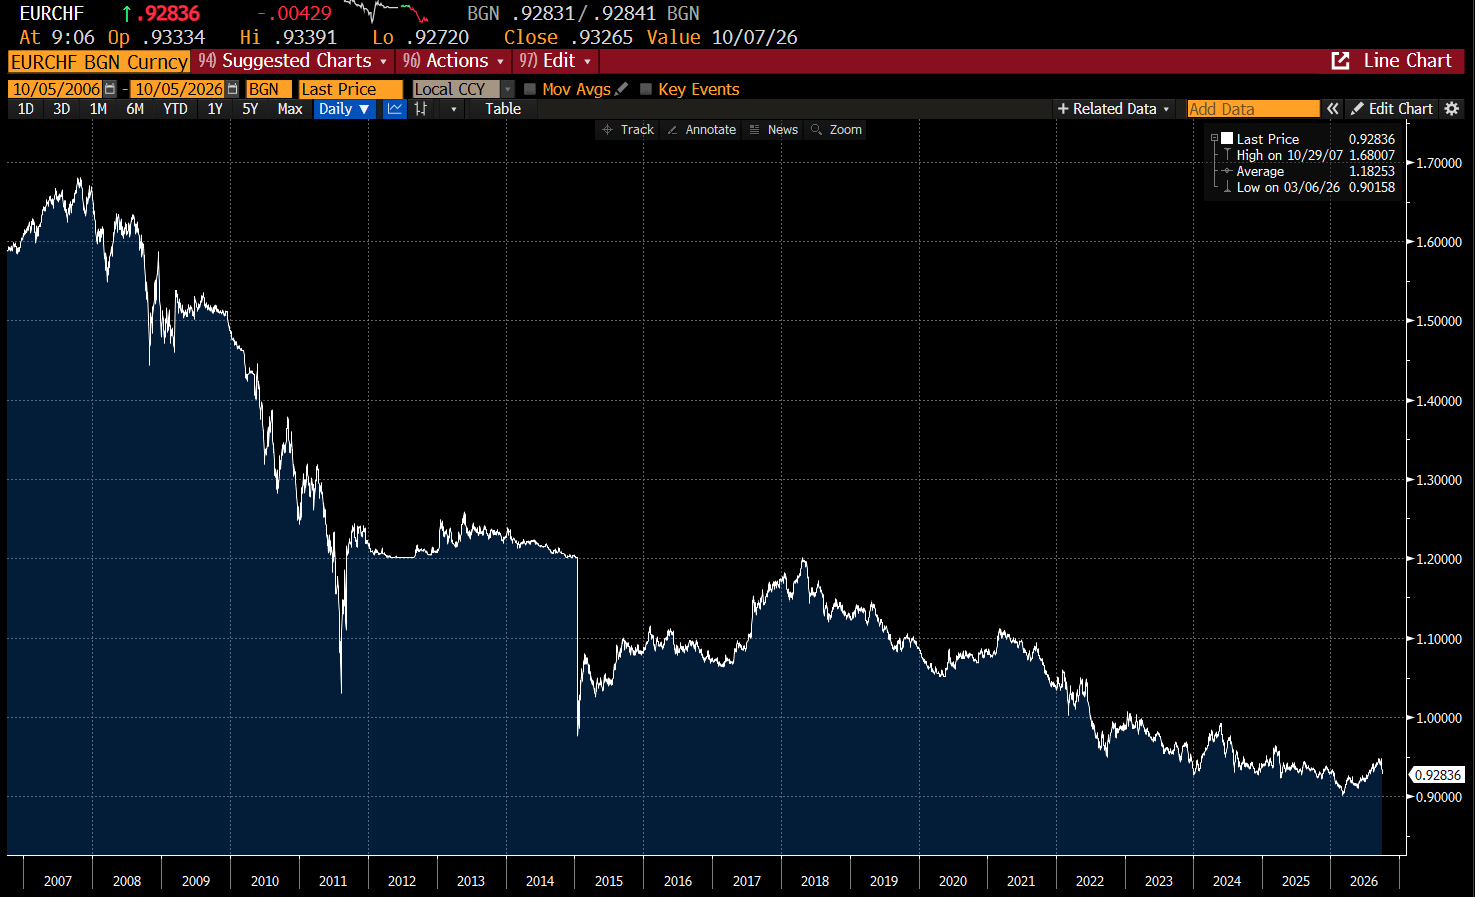
One of the weird things about the “French bond crisis” is that until this month, Euro was strengthening against the Swiss Franc.
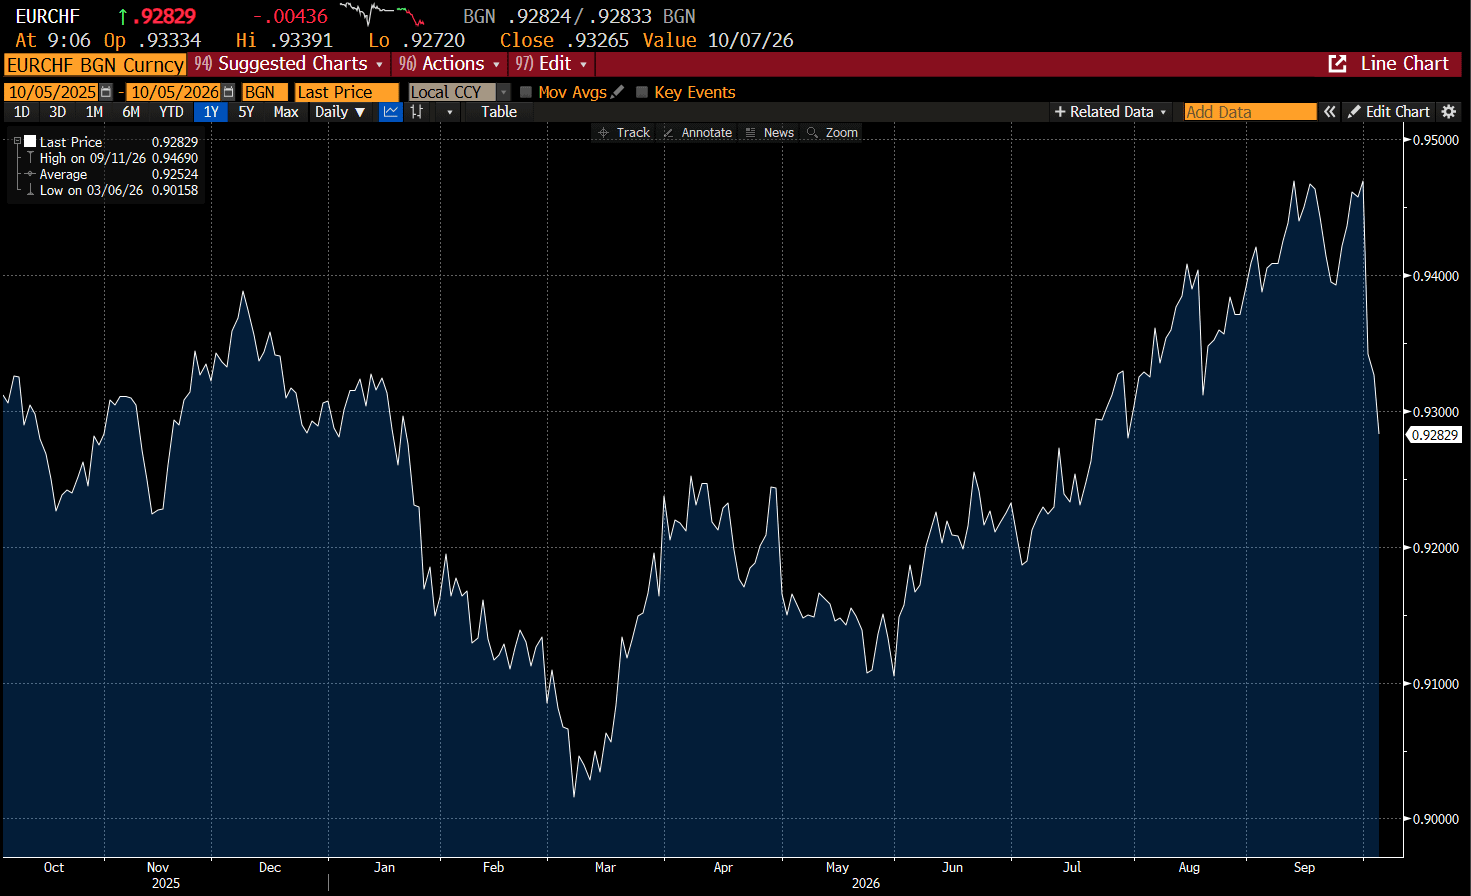
Since the beginning of debt problems in 2007, you have tended to want to be long Swiss Franc vs Euro - but as of today, CHF is no stronger versus Euro than in 2024. Very odd behaviour indeed. Why?
One reason may be the French political reaction. I was stunned to see that Marine Le Pen has suggested a debt brake be added to the constitution.
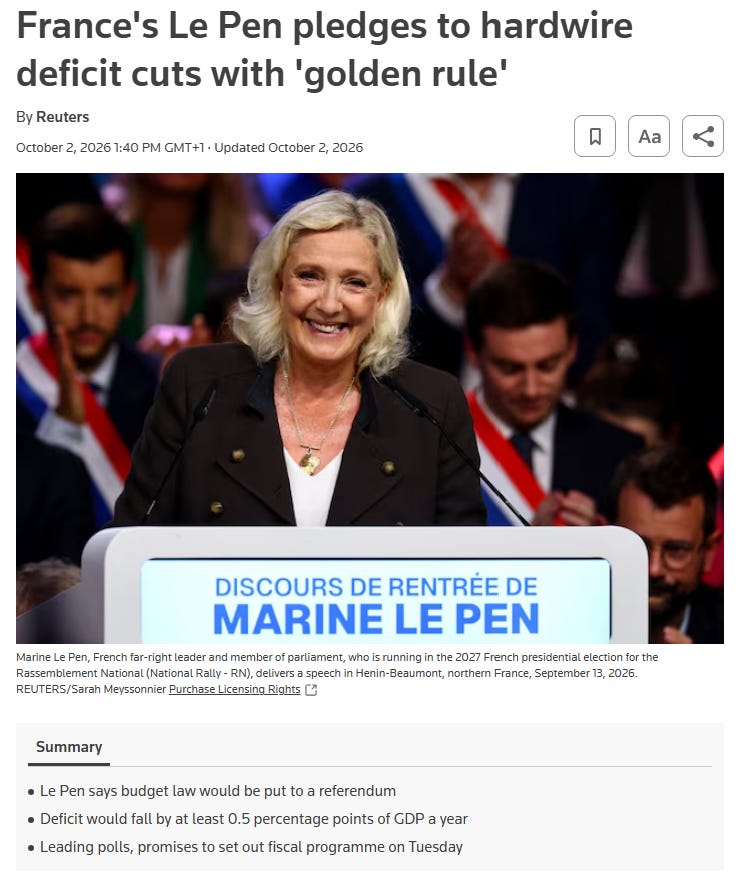
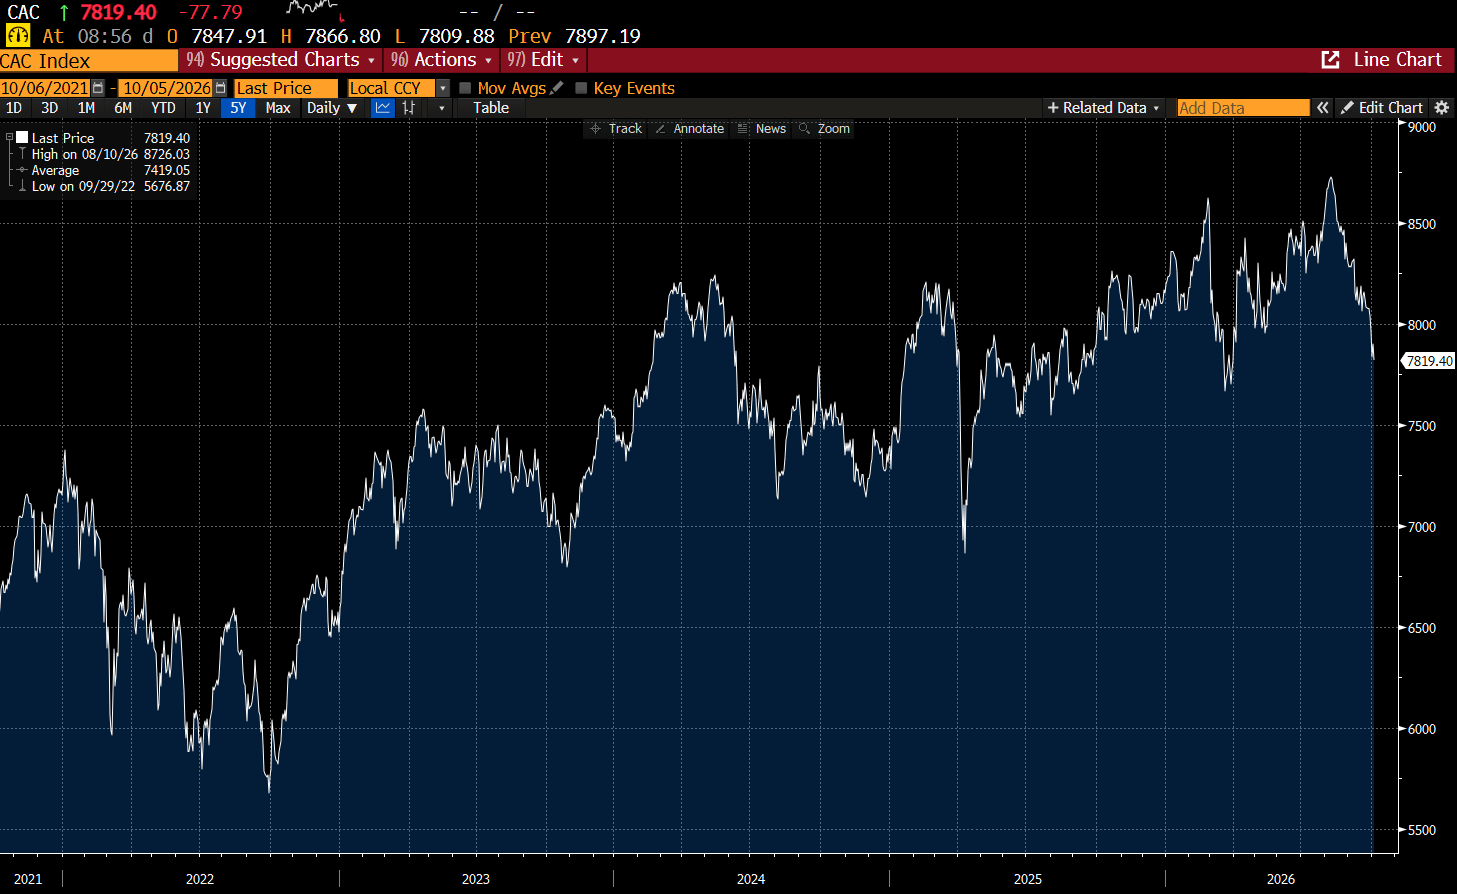
I find this very bullish for the French bonds if implemented (big if), but also seemingly send a big signal that Le Pen is not seeking to leave the Euro. This is also “deflationary”, and has been reflected in the stock market.
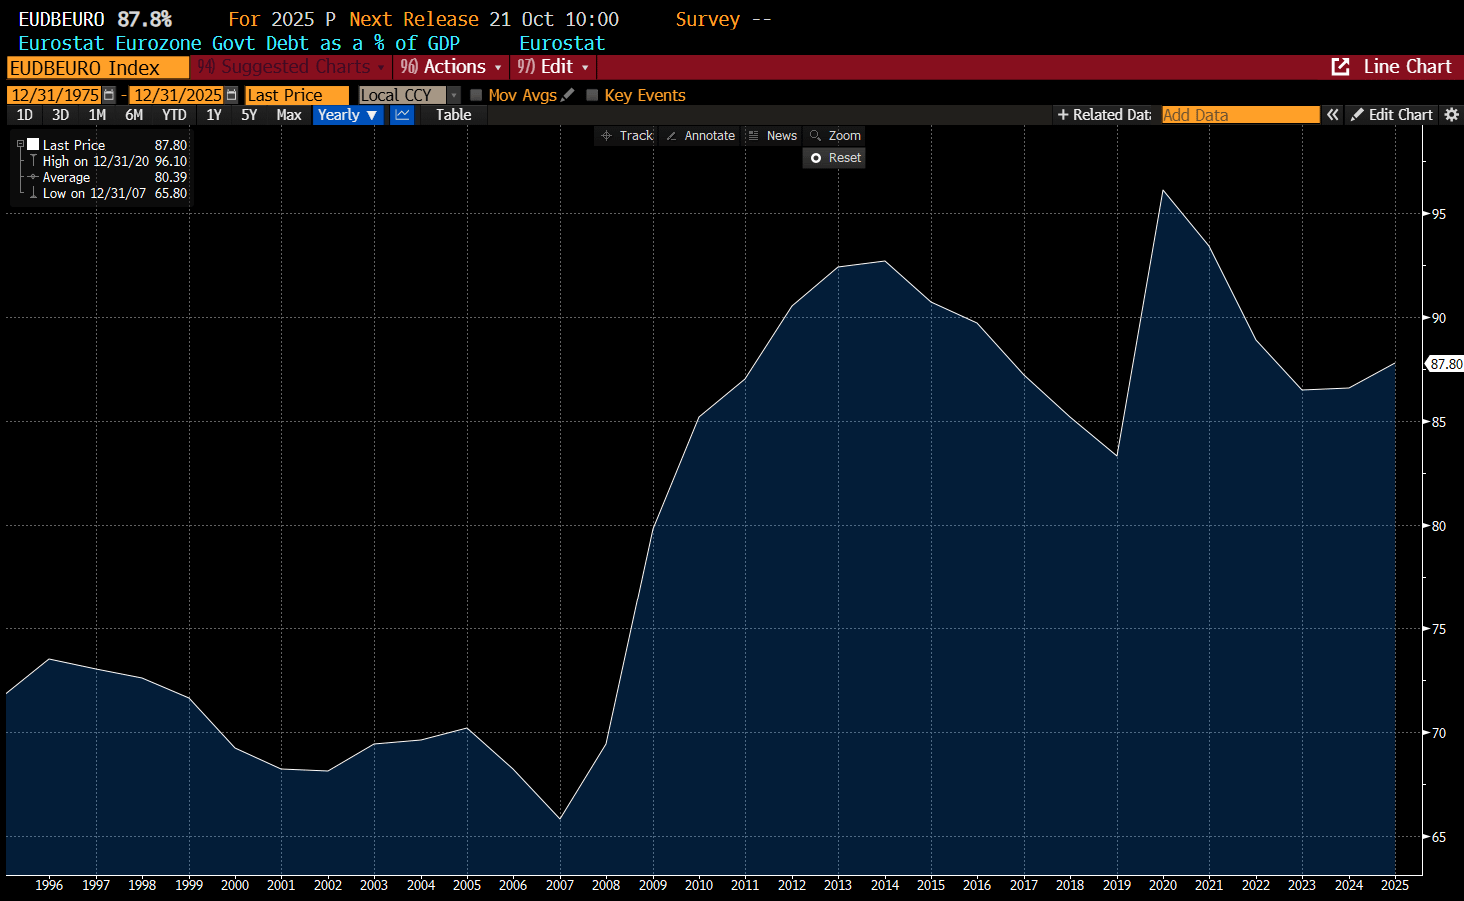
What I find so interesting about the current set up, is that the macro signals are very bearish Euro, while the political signals would be bullish. Eurozone debt levels as a whole are very manageable.
In both Italy, and now potentially France, the populist leaders have signalled a preference for fiscal consolidation. The biggest headwind for the Euro has been very expensive energy prices. TTF Gas is back at USD 24, a big premium to the US prices, and so a competitive disadvantage.
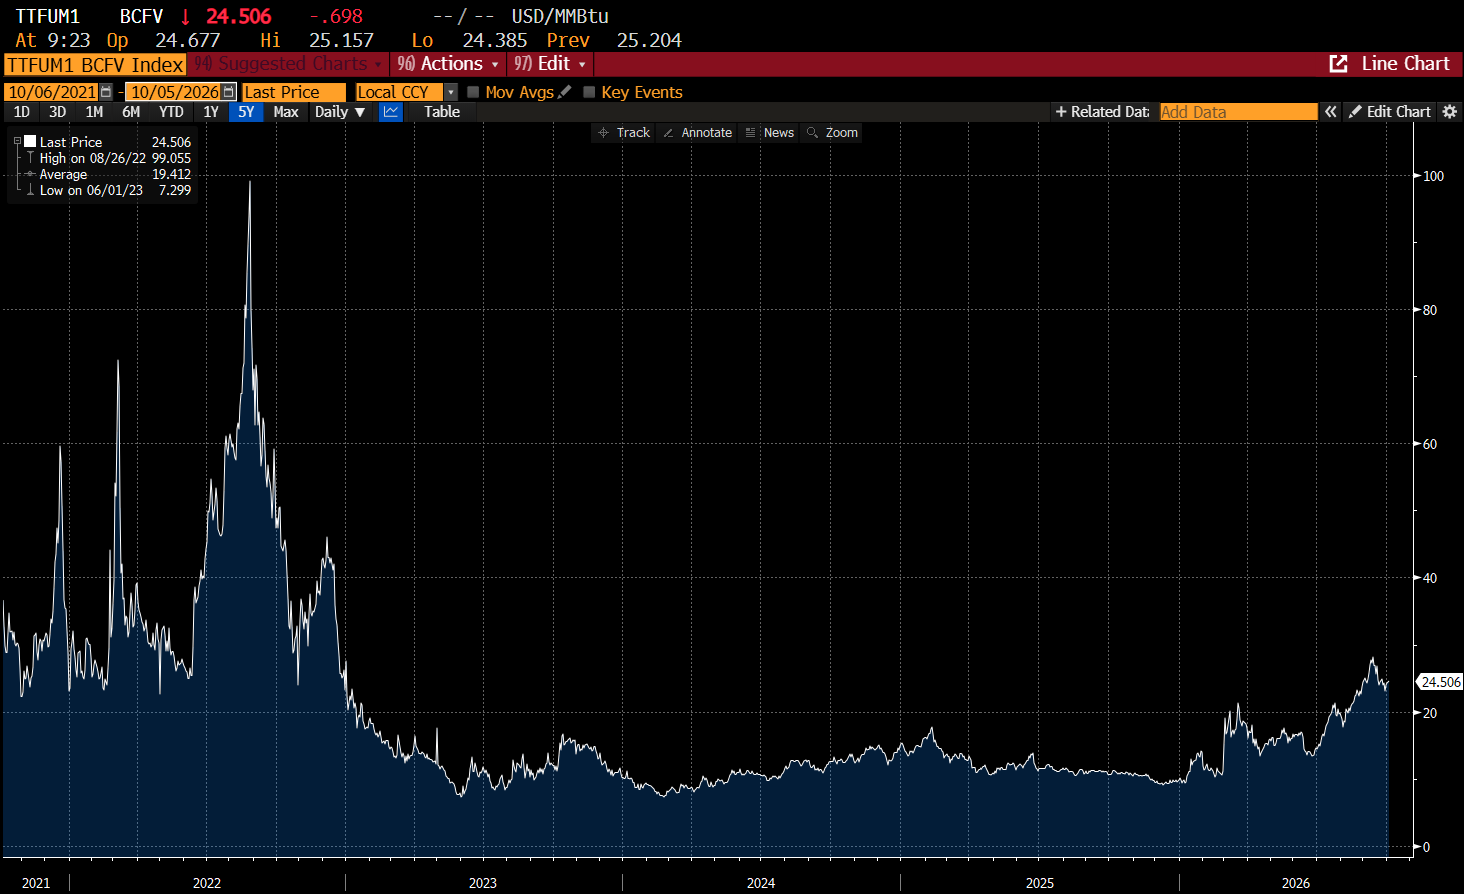
But while higher energy prices led to collapsing activity in Germany in 2022 (most reliant on cheap energy), in 2026, there has been no noticeable decline in PMIs in Germany.
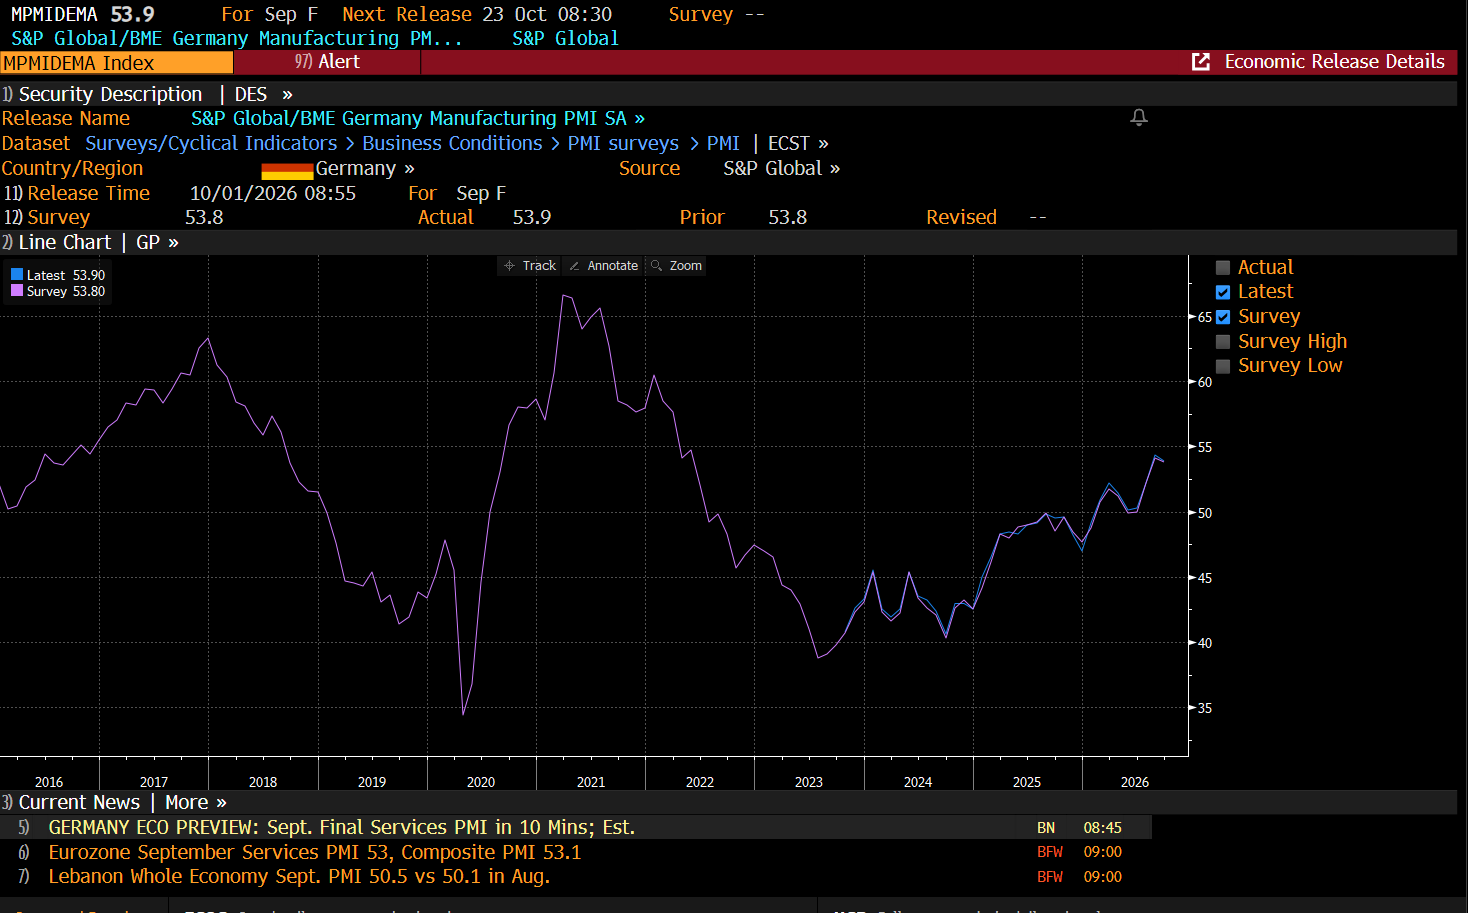
All of this reminds me of something that I learnt when first starting to managing money. Almost all US statistical releases get revised downwards, and almost all European statistical releases get revised upwards. Here, we are focused on the price of French bonds, but not on the political response or even the surprising strength of European economic data.
Old school macro models will probably be bearish Euro here, while I think the politics is bullish. For the last few years, political analysis has won over macro analysis. Lets see if that happens again.


