
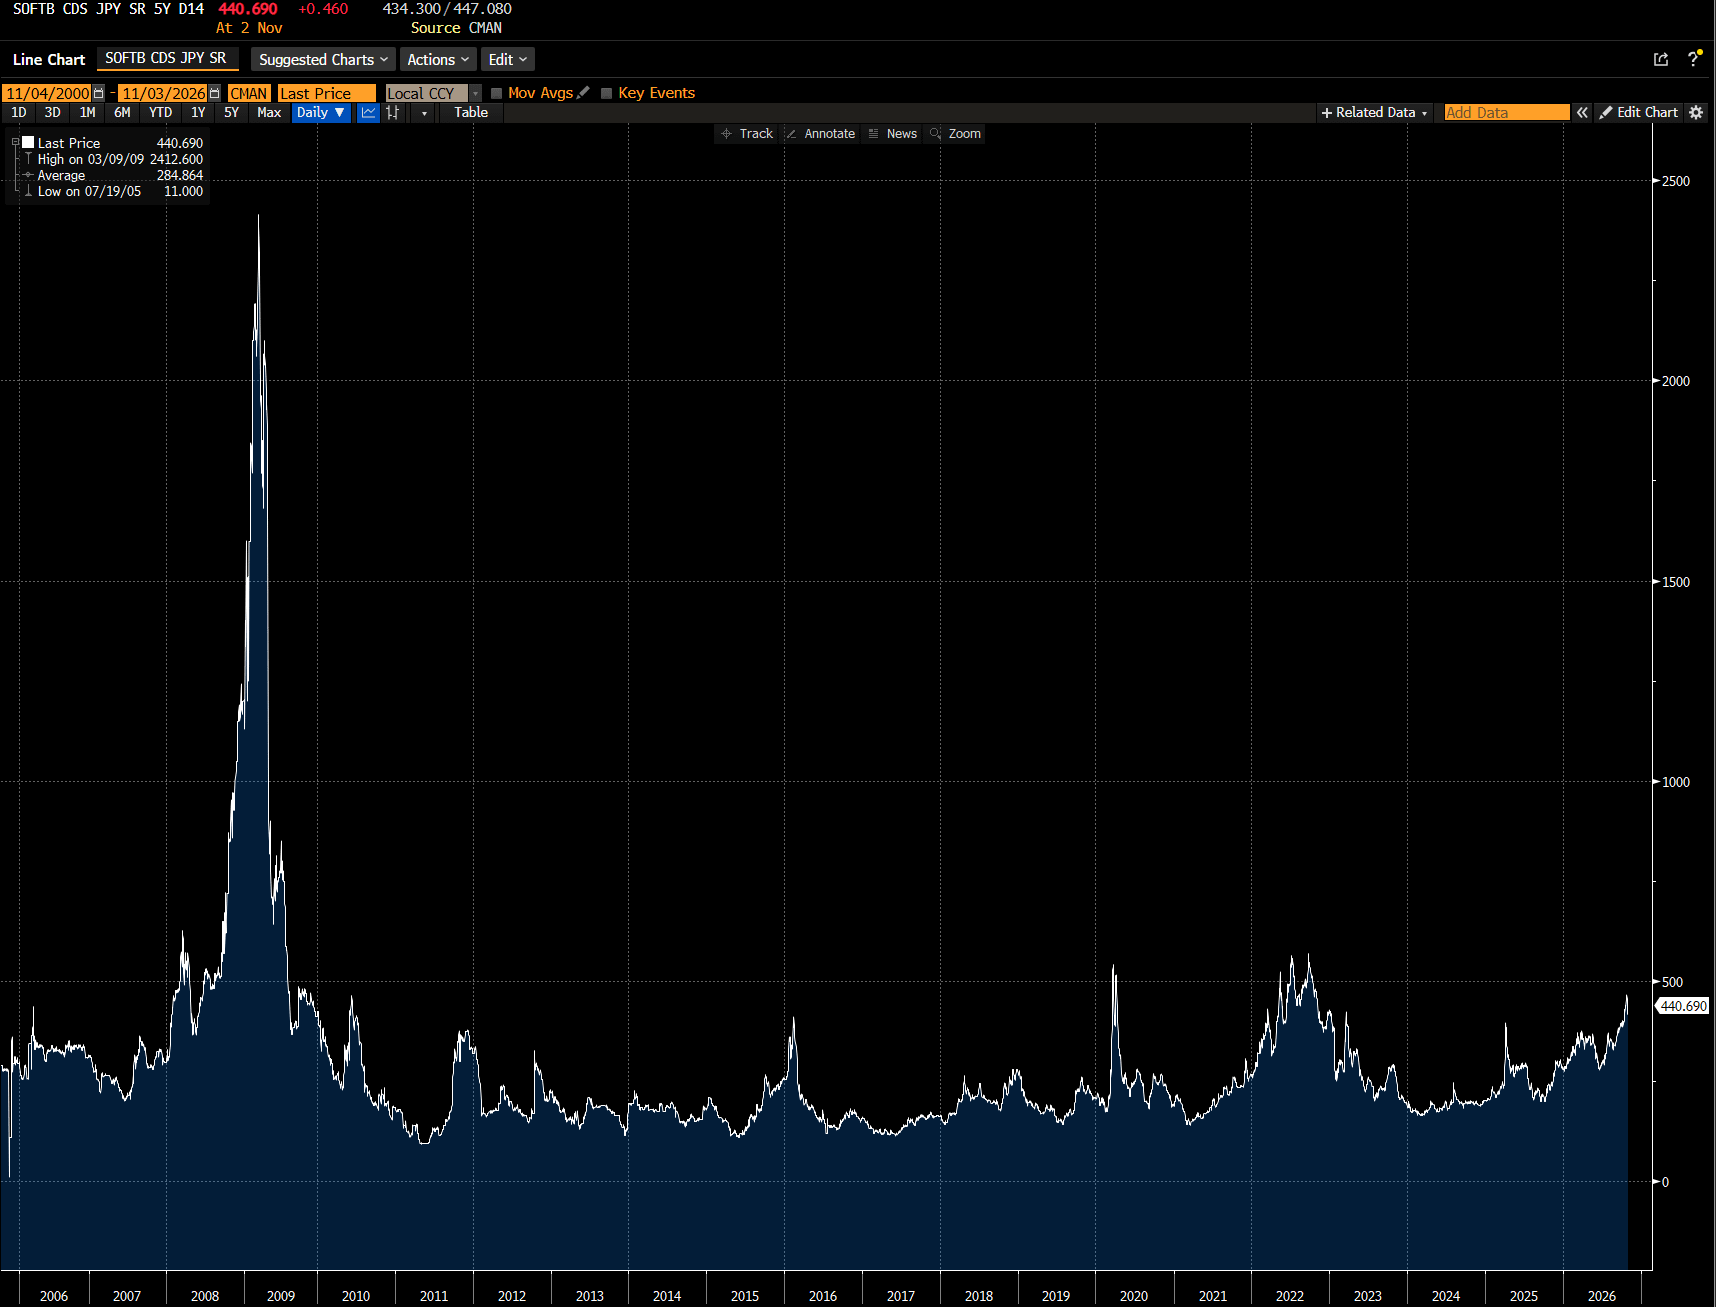
Earlier this year, I thought Softbank was worth a short. It had just raised debt at an 8% yield. Like many names in the AI space, its CDS were implying some problems.
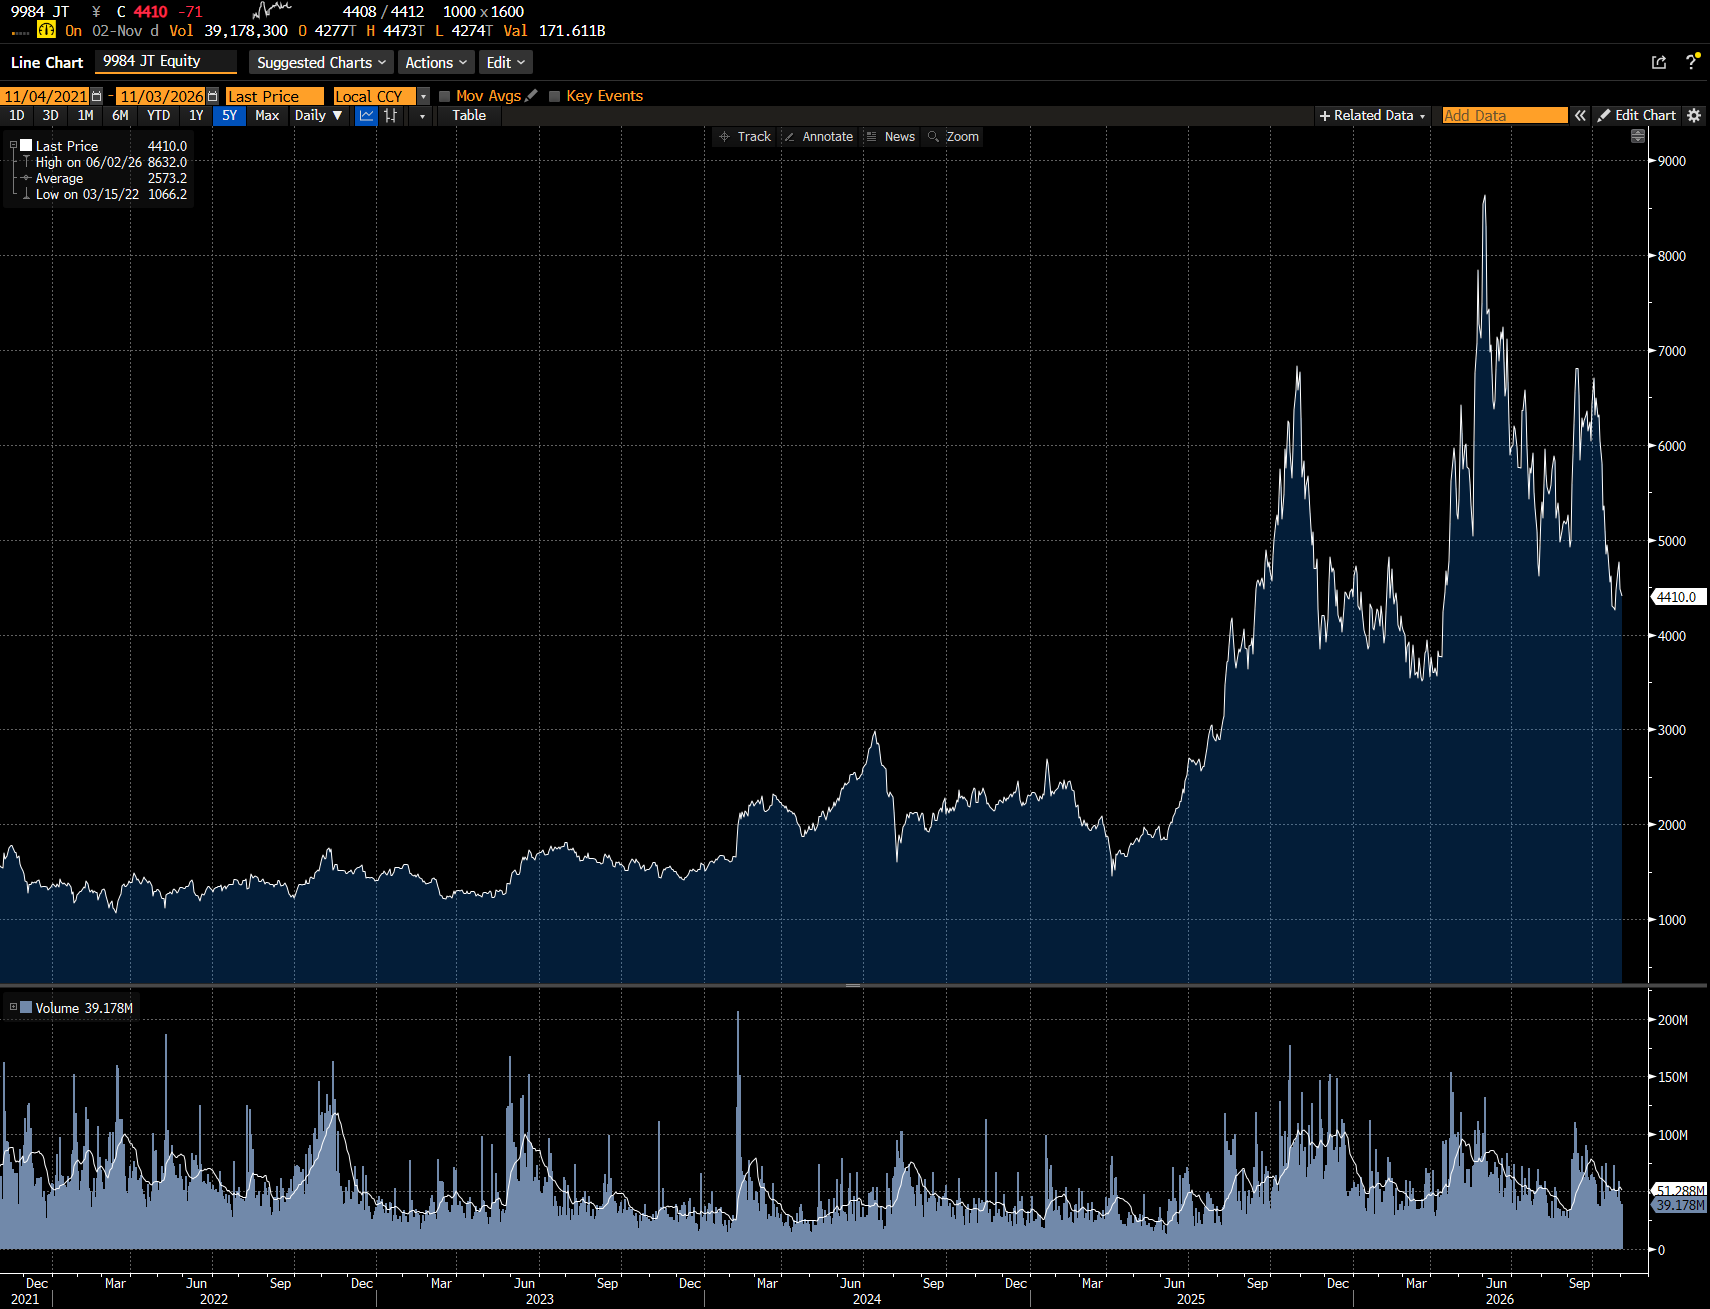
Usually, rising CDS is associated with equity weakness - but in Softbank’s case, shares have tended higher, if extremely volatile.
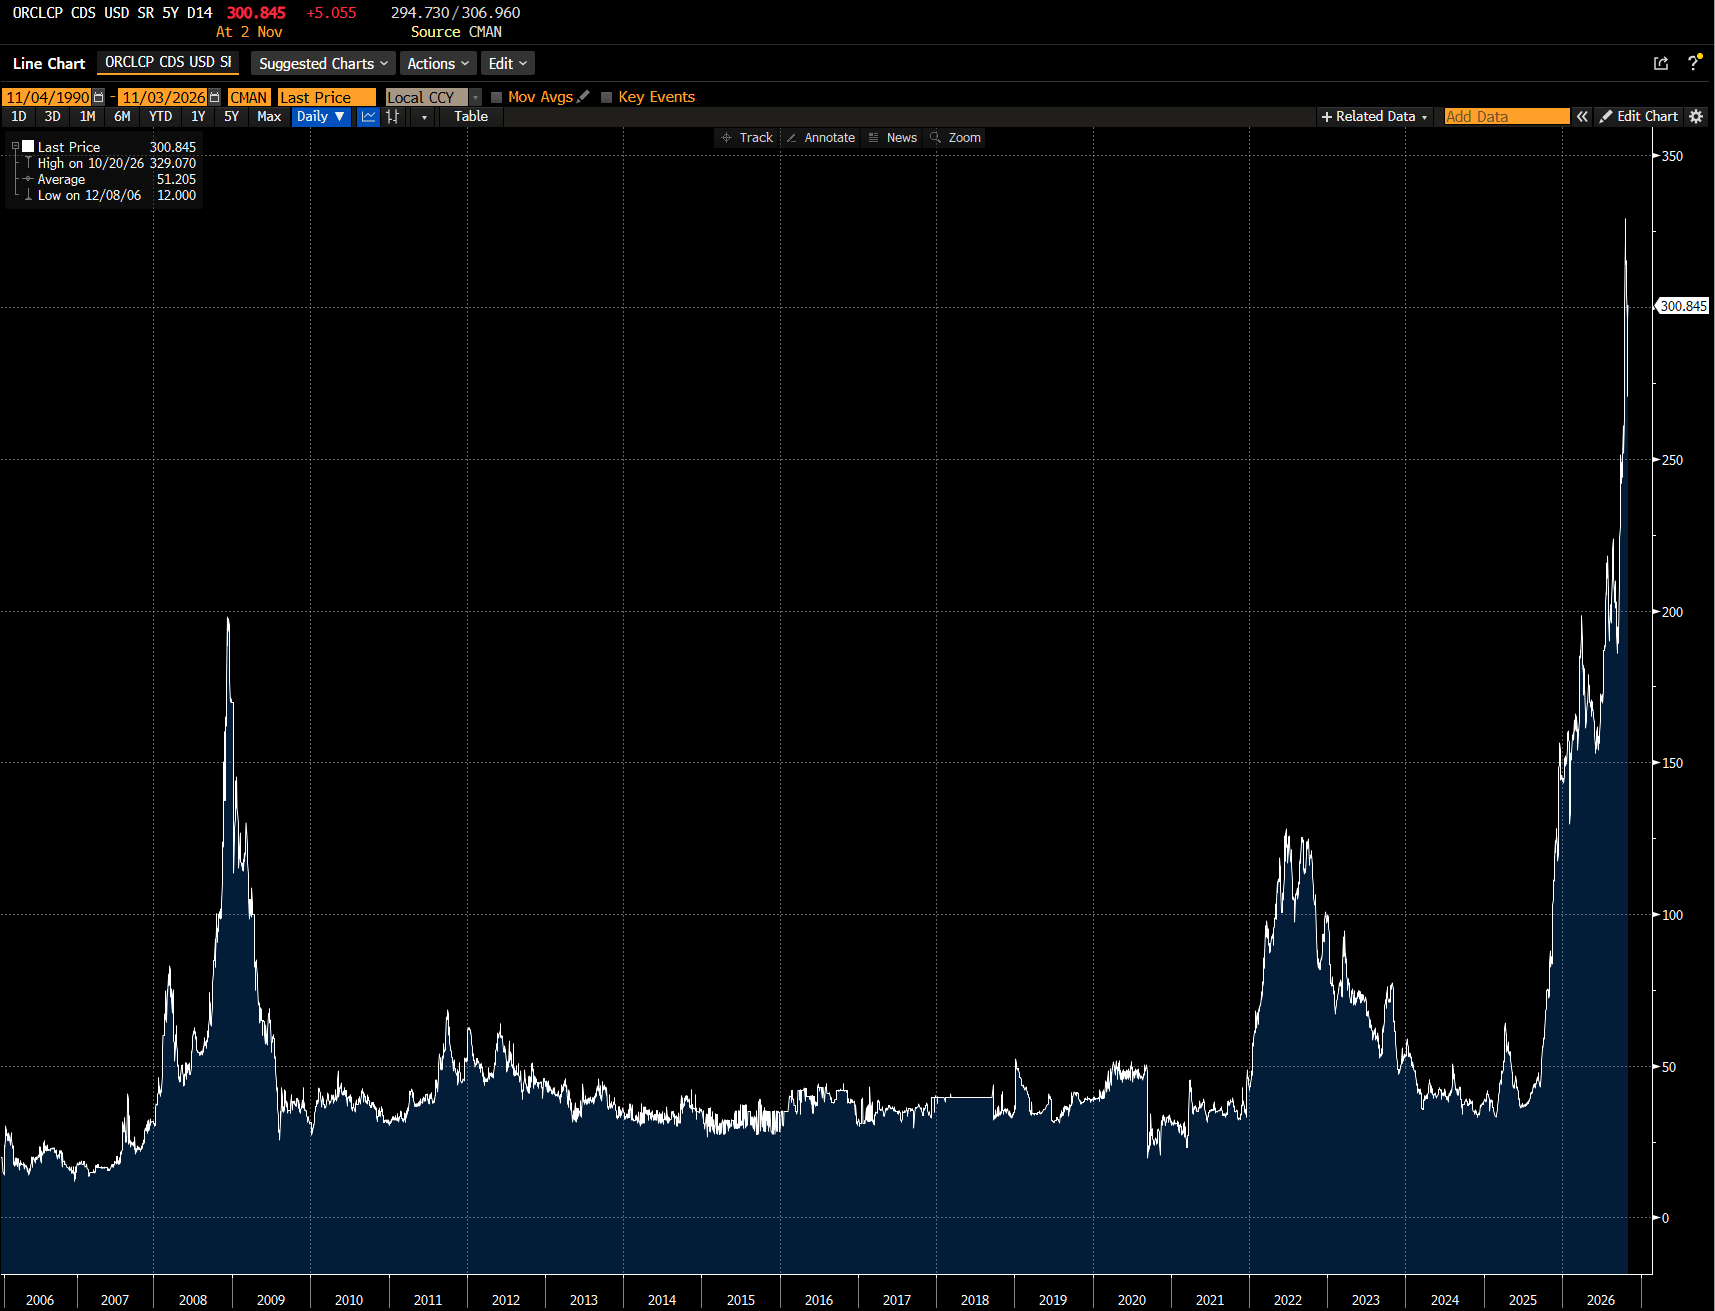
This in contrast to Oracle, where equity valuation as CDS has risen. Oracle CDS has even exceeded 2008 highs.
And in Oracle’s case shares are down 60% from a peak.
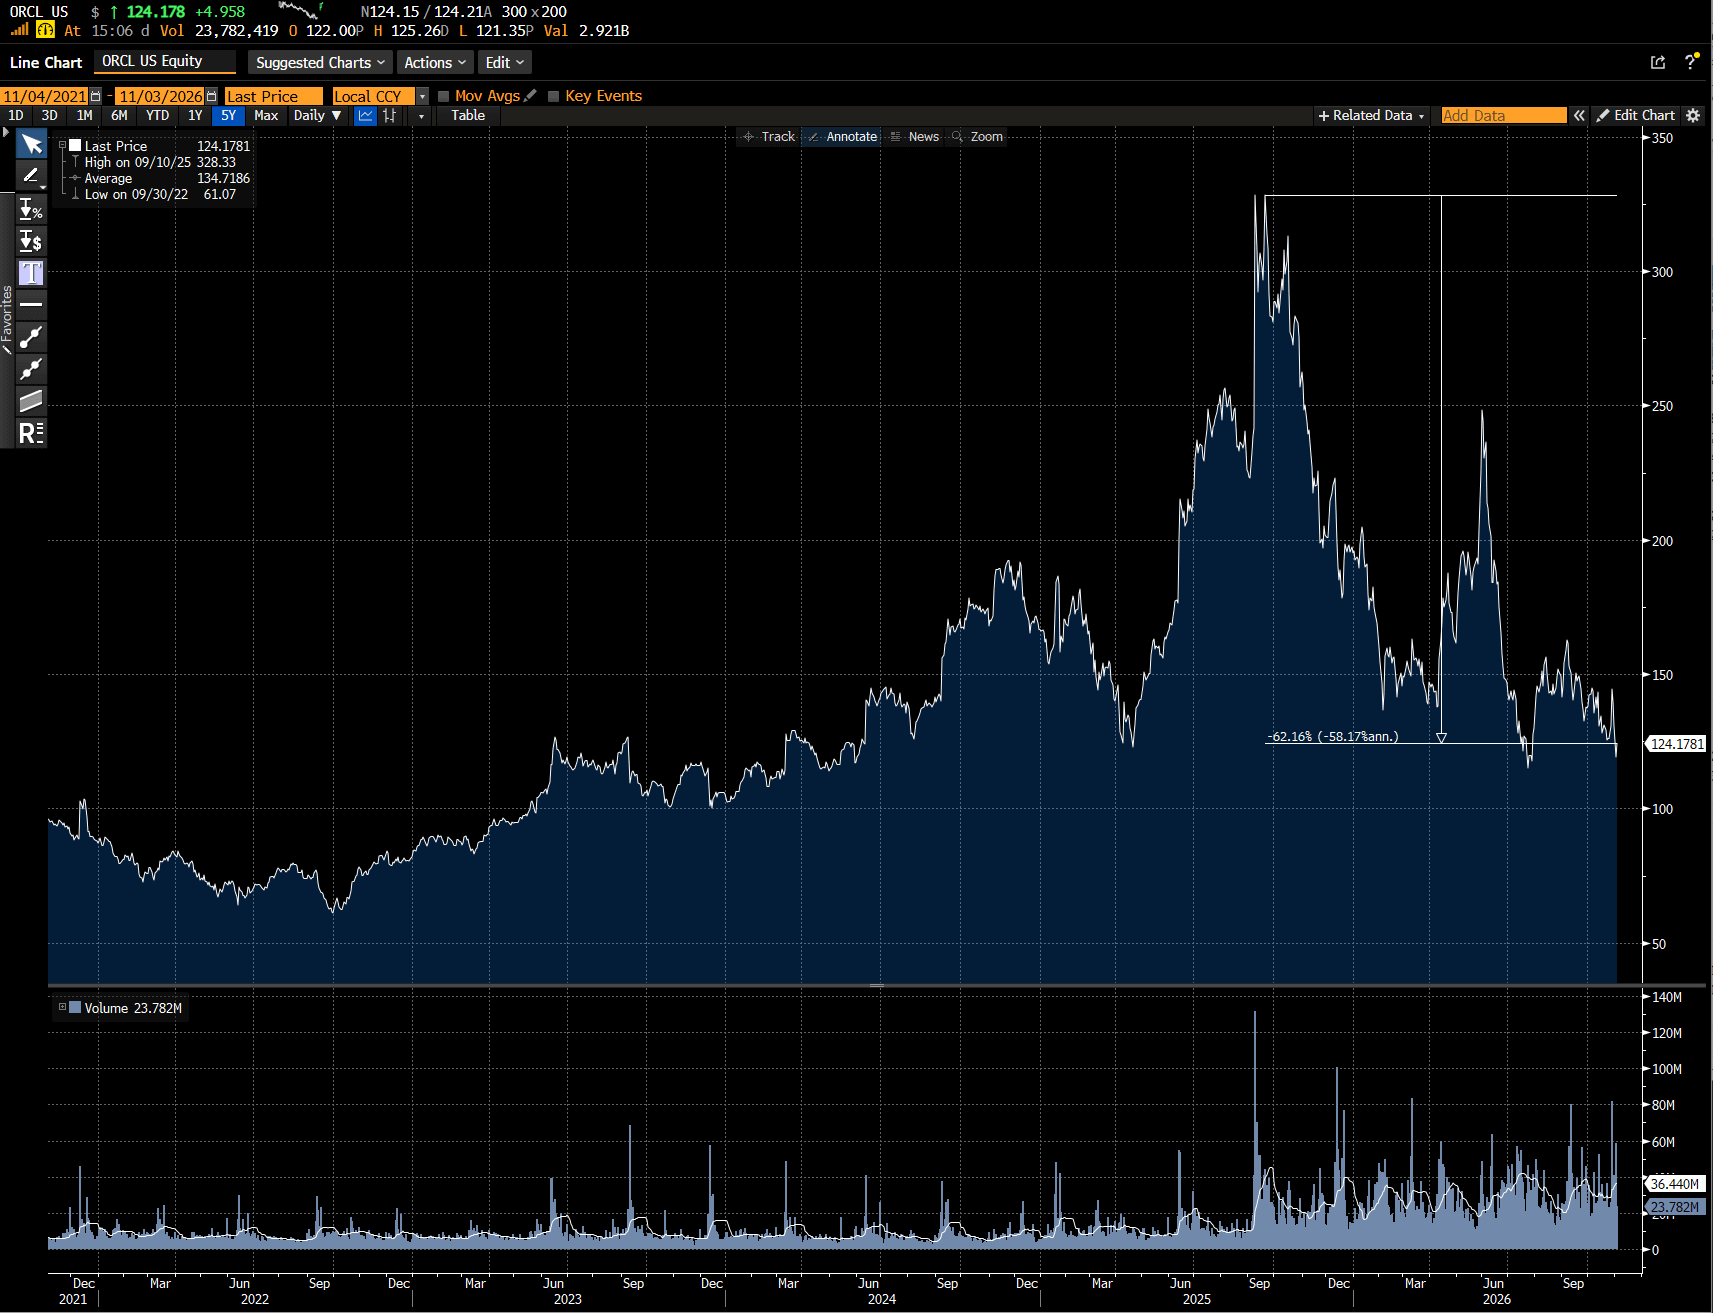
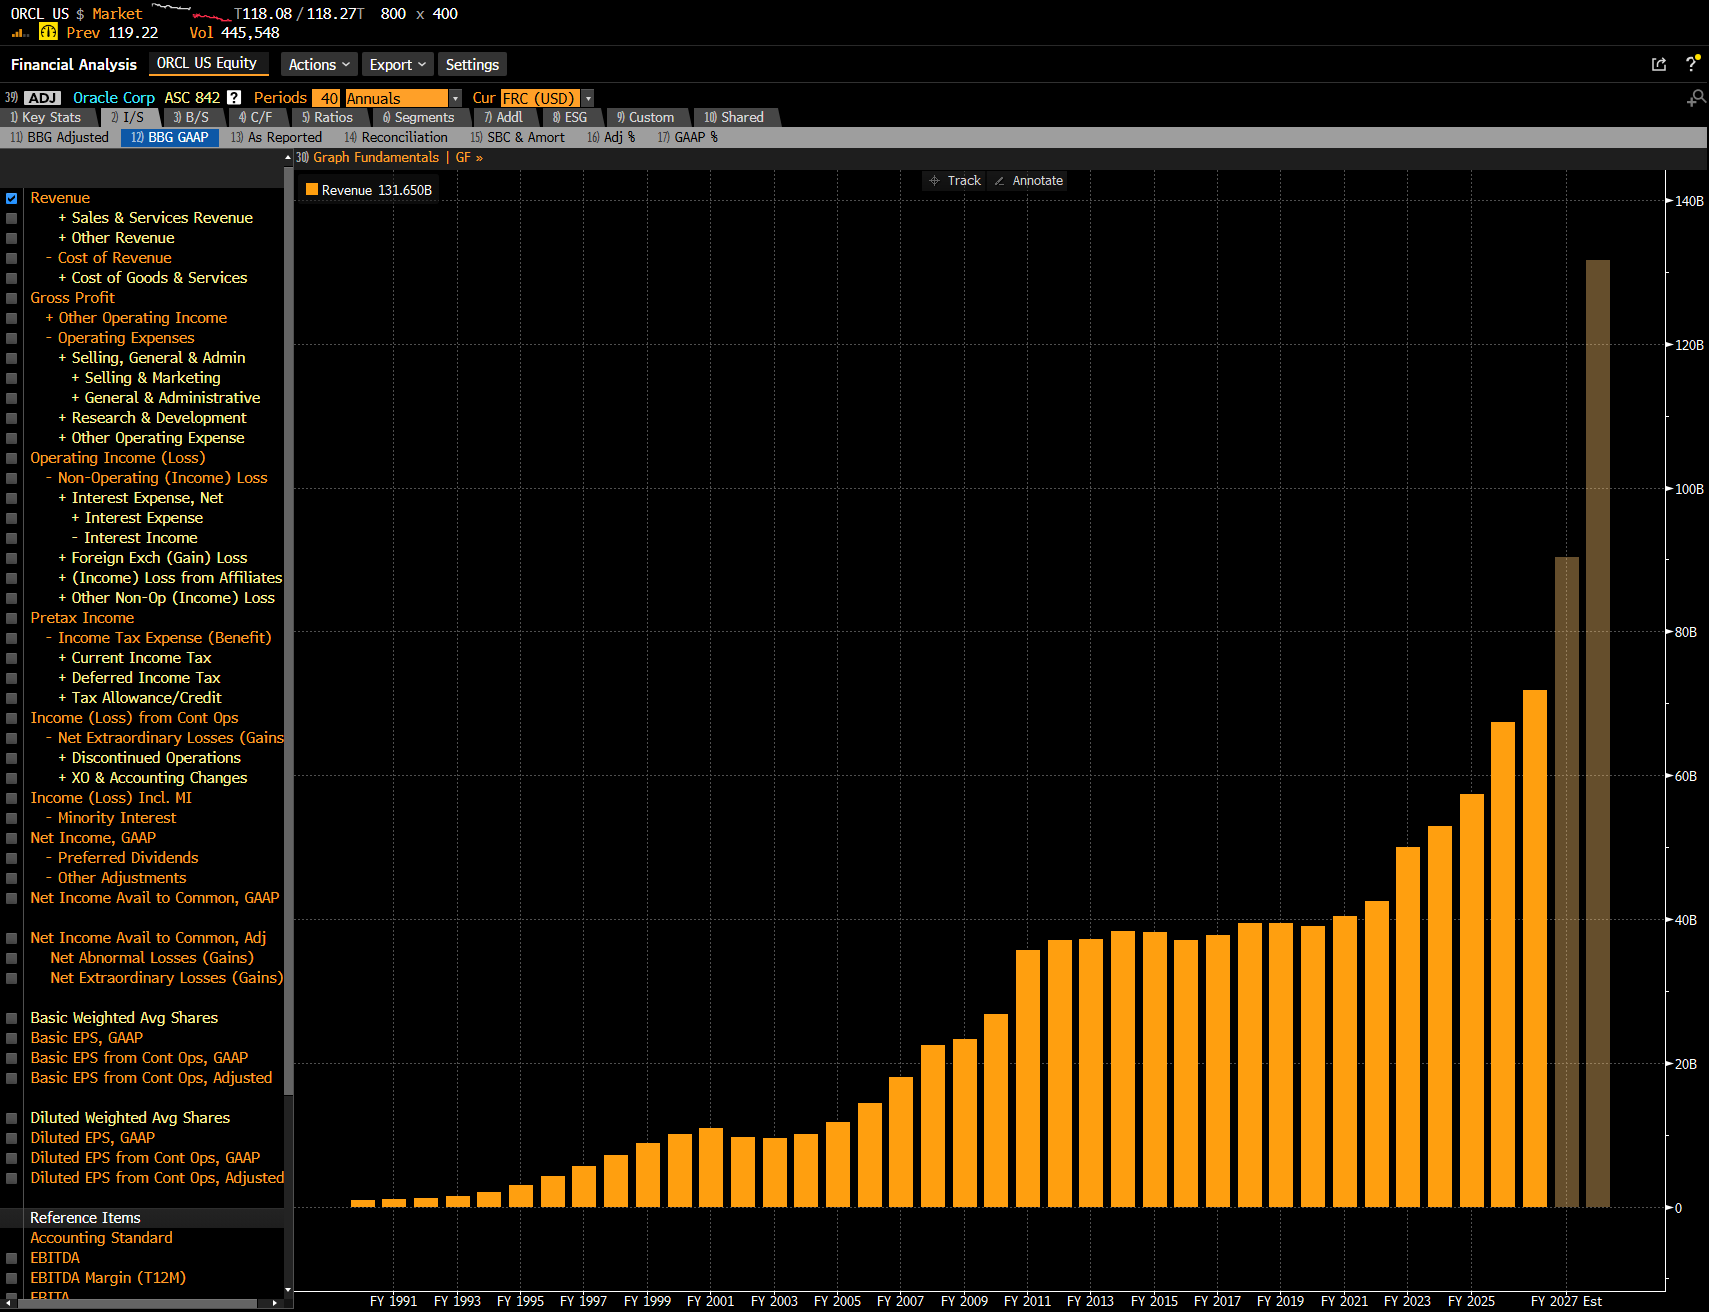
Just looking at the share price above, you would assume that the dot com bust was already upon us. This is not the case, revenue growth has returned to Oracle after a decade of stagnation.
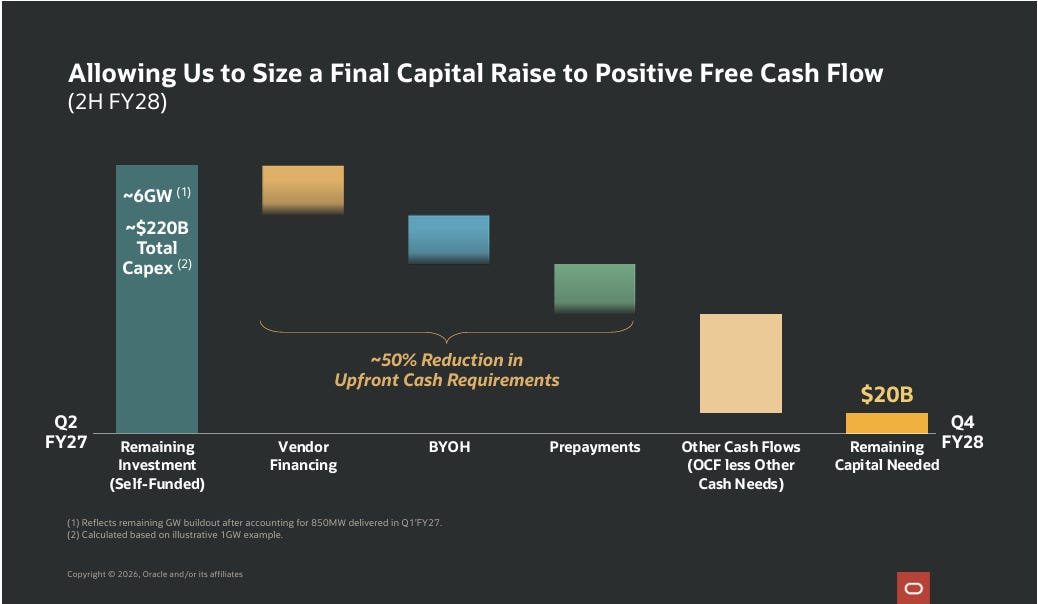
In the most recent quarter, Oracle seems to have responded to share price and debt pressure, and found ways to cut capex. I would expect this to be nominally bullish - but so far nothing.
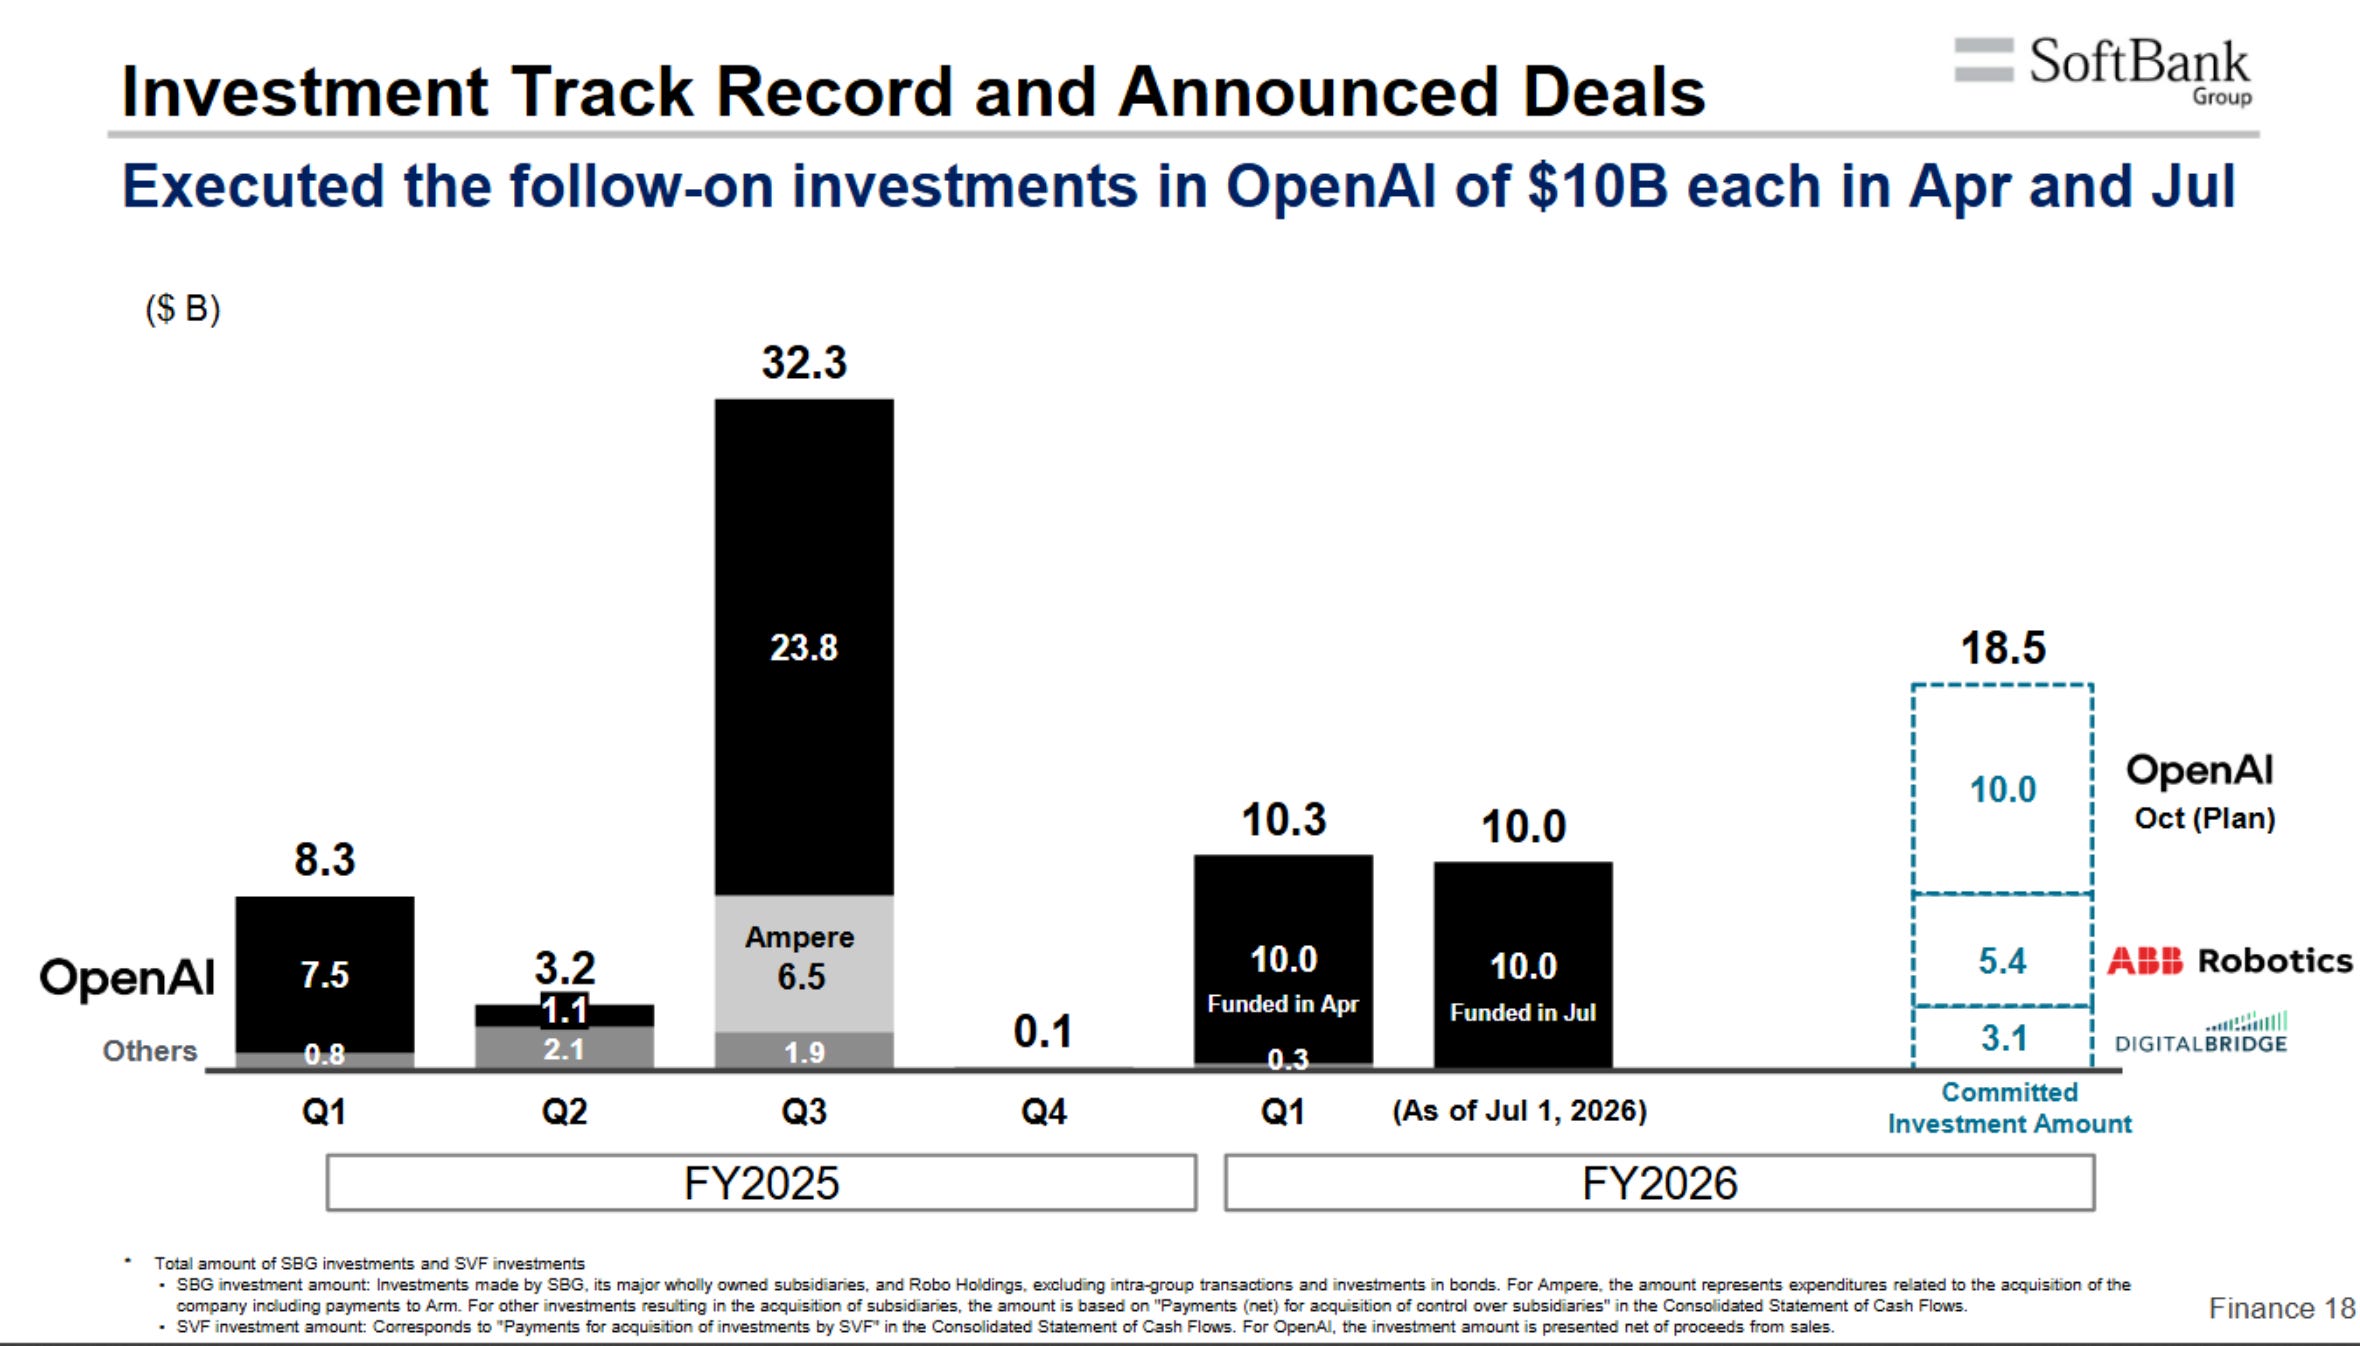
What links Softbank and Open AI? Softbank is the biggest investor in OpenAI, and OpenAI is Oracle’s biggest customer. In other words, Softbank provides capital to OpenAI, and this capital is then used to fund the growth that Oracle is investing to supply.
The big question is whether OpenAI can actually meet the commitments that it has made to Oracle. Some rough financials for Open AI are below. We can see from most recent filings that Anthropic is seeing USD 17bn of revenue for Q3 from USD1.3bn a year ago. So the revenue forecast for OpenAI for USD 70bn in 2027 looks achievable. The question is whether they can find the capital for the USD 300bn of forecast funding.
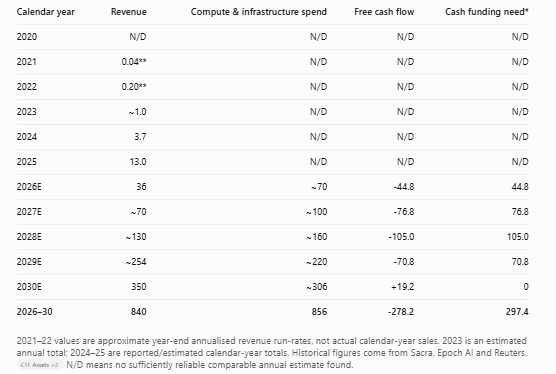
If you are bearish, you can say there is no way that OpenAI and Anthropic can raise the cash they need. Whereas, when we look at SpaceX another company with big growth ambitions, it has raised USD100bn this year, making it the largest IPO of all time. That is OpenAI could get the capital from equity markets, as long as they stay open. In 2021, nearly USD 600bn was raised from IPO markets.
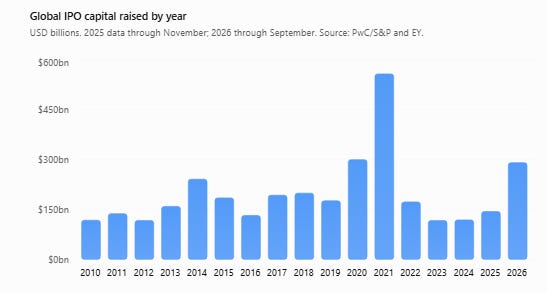
That is the key issue. Can Anthropic and Open AI raise the capital for the growth forecasts? Or in other words, can and will the IPO market stay open? With debt markets expensive, the IPO market becomes all important. And IPO’s can be all about narratives. Tesla and now SpaceX are good examples. Both listed at extremely high valuations (EV/Sales of over 20), which provided the growth capital they needed, and the financial safety to tap debt markets.
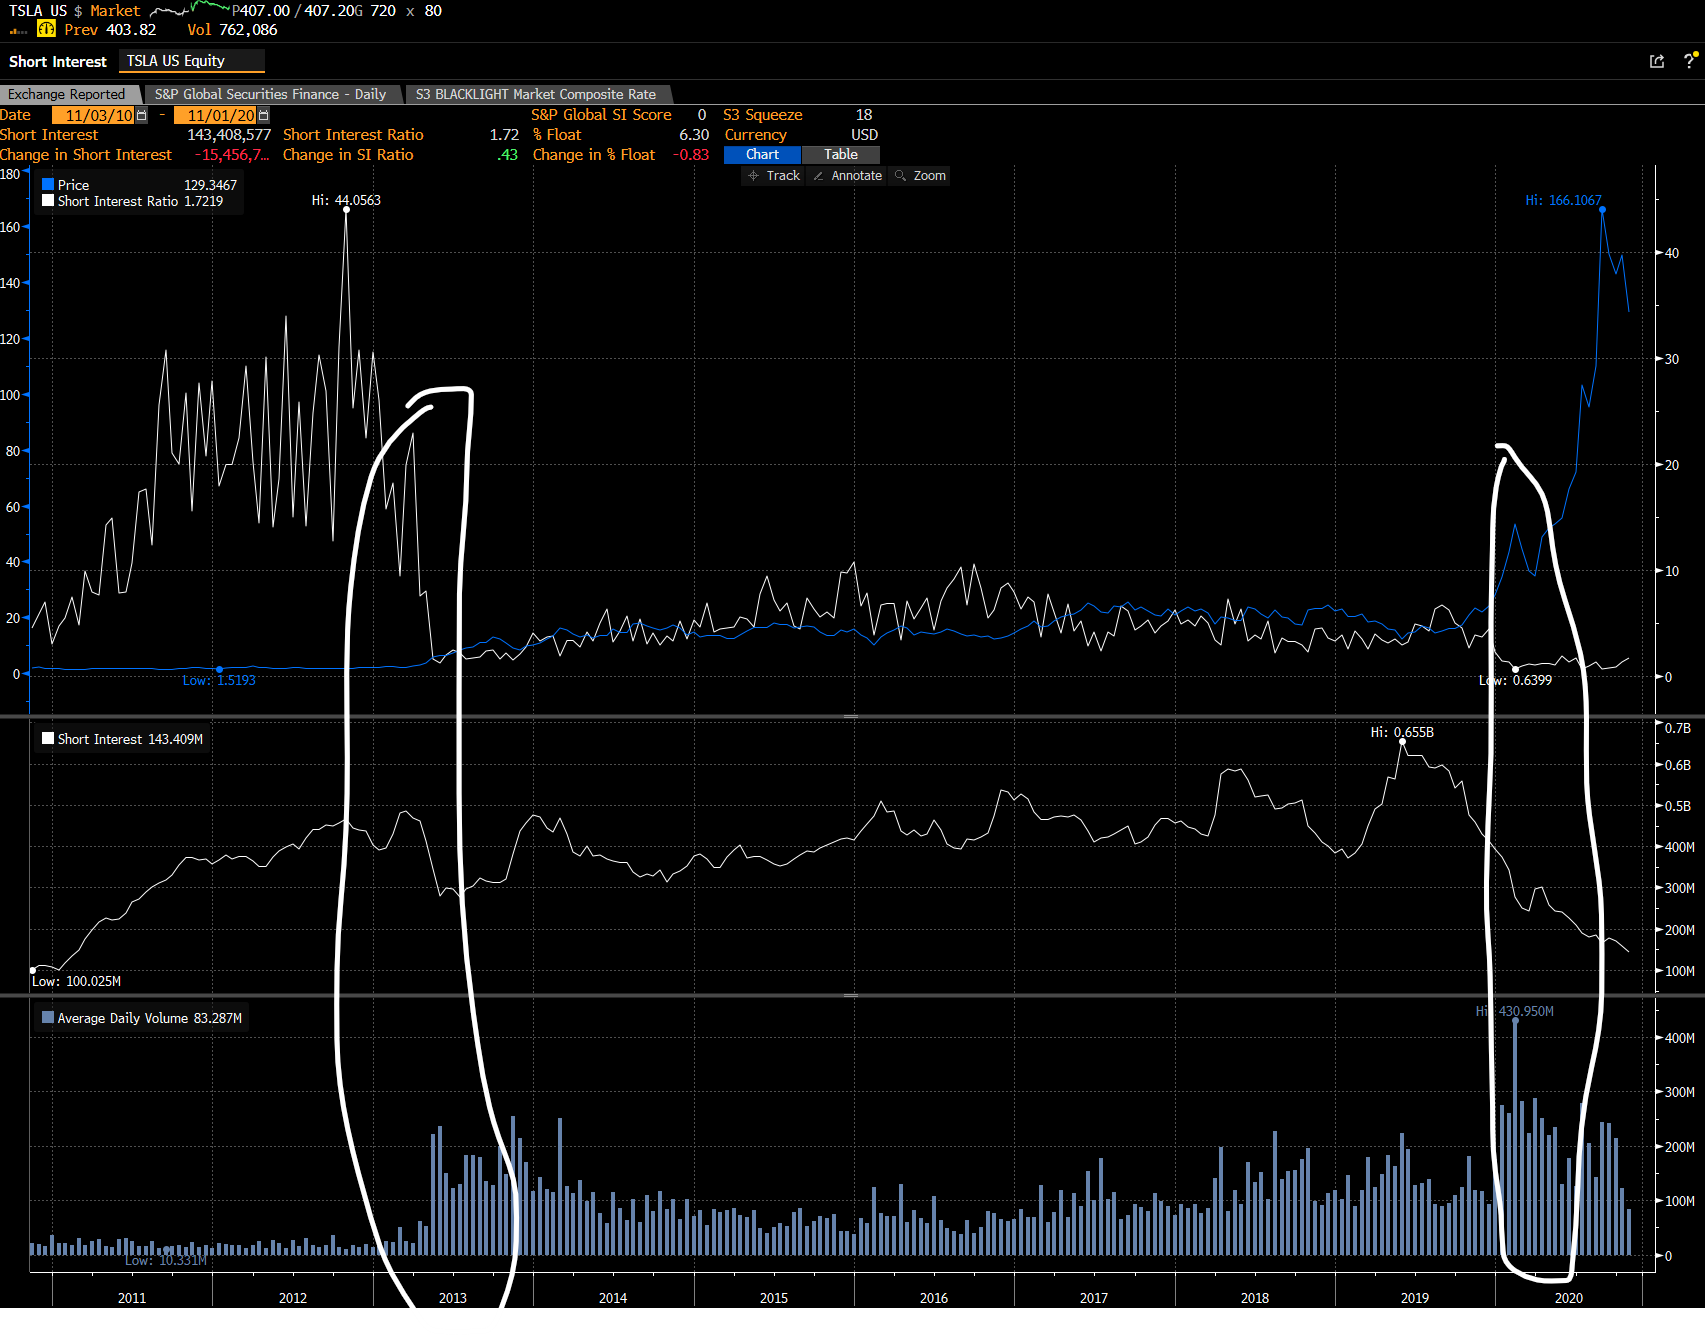
But IPO markets tend to be about narratives. In this case AI is going to take over the world, or it is just a capital destruction machine? The thing about narrative wars, is that the bears almost always lose in my experience. Tesla is probably the most relevant example. When it first listed, it was obvious that it needed more capital. Hence it attracted large short interest, but this inevitably lead to a short squeeze, which provide a more attractive level for Tesla to sell equity, which reduced the assumed dilution, which forced the valuation up, and so on and so forth. You can see short covering tended to occur with equity raises with Tesla. you can see how volume traded increased as equity was raised.
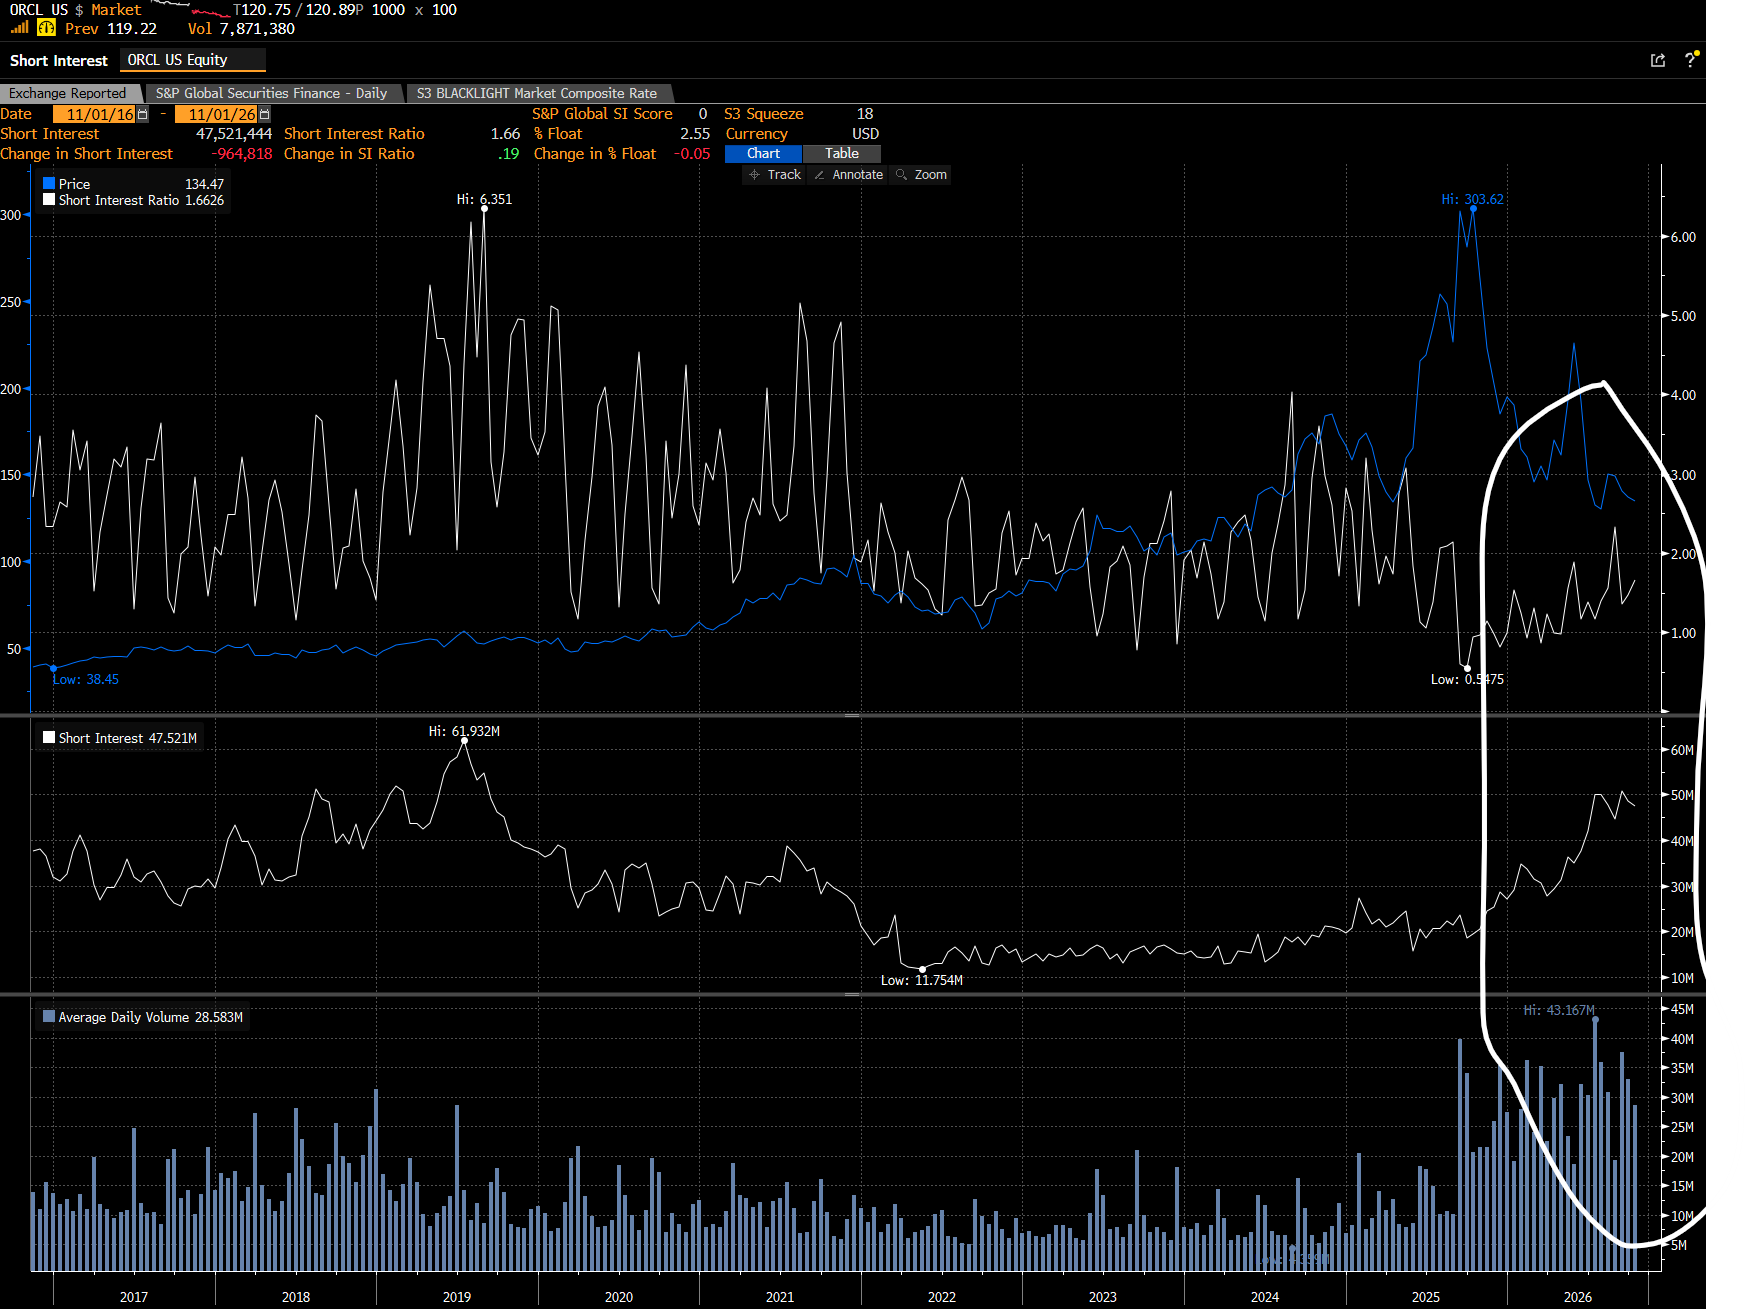
Short interest in Oracle is now elevated.
You might think Tesla was a one off occurrence - but we saw a similar dynamic with Strategy. Very high short interest led to Strategy pricing above NAV, giving the company the incentive to issues shares to buy Bitcoin, which helped created the upward surge in the cryptocurrency. As short interest has waned, crypto has struggled.
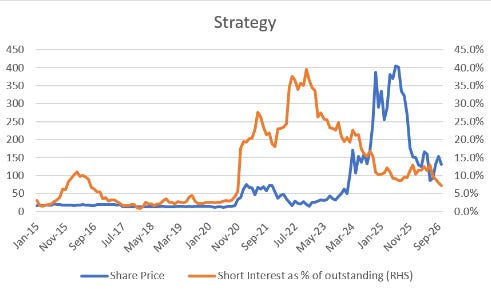
The problem with winning the narrative war, is that bearish bets create the conditions for a company to win the capital war, which ironically would not have existed without the bearishness. Every short is a confirmed buyer at some point. And every short will have borrowed from a long owner, who cannot sell. The bears are winning the narrative story - but they are unlikely to win the capital story.


