
I have been a little blindsided by the move in GLD/TLT this month. Gold has gone down, and TLT has gone up. Technically, GLD/TLT has gone through its 200 MDA, and the 200MDA is threatening to turn lower for the first time since 2020.
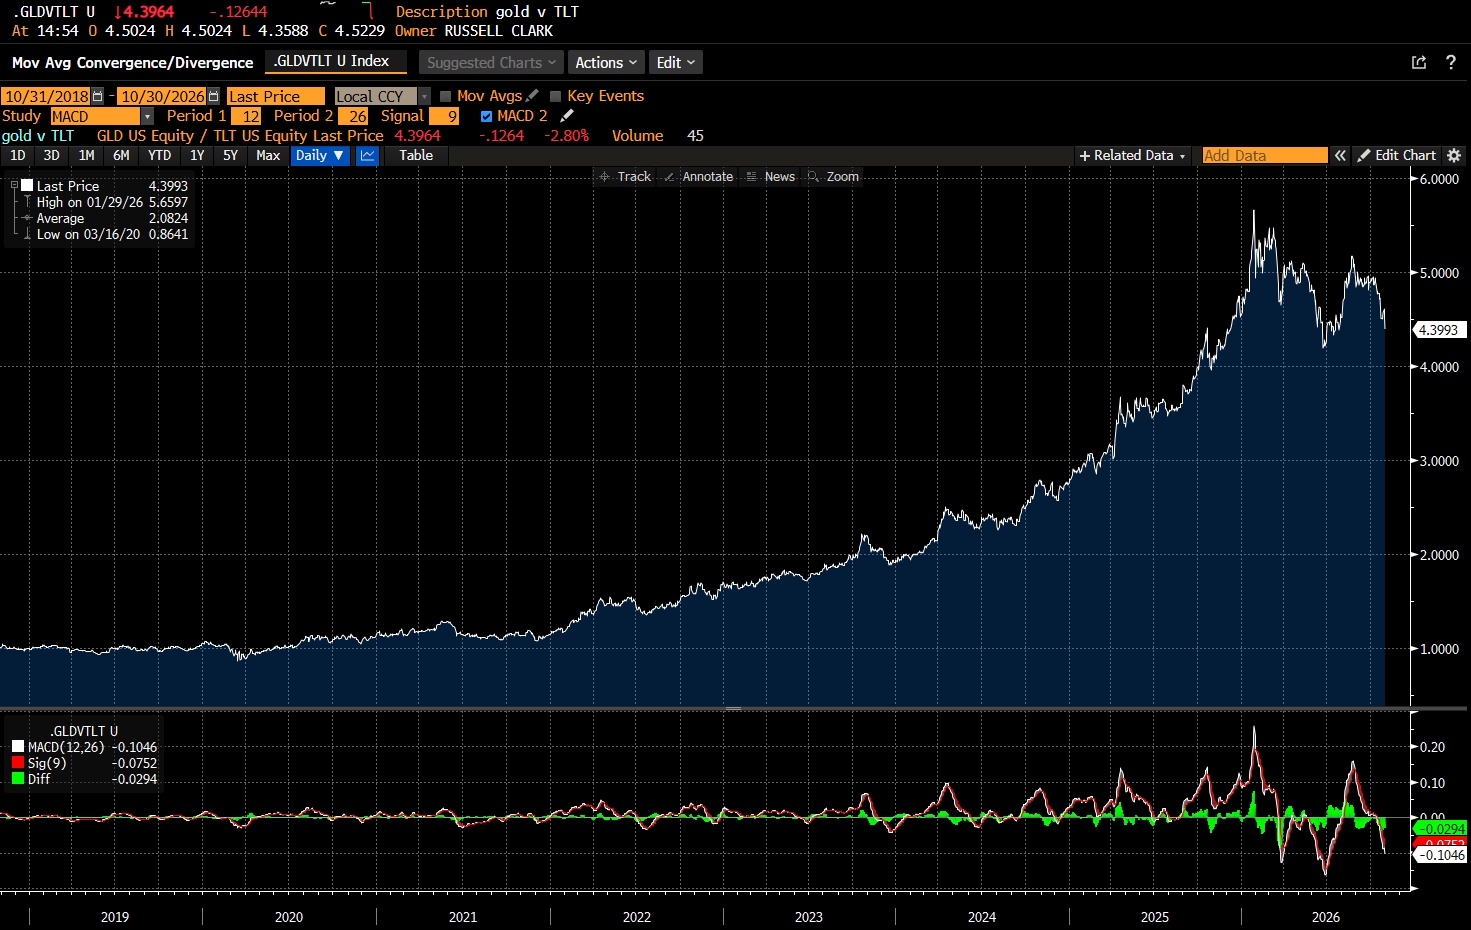
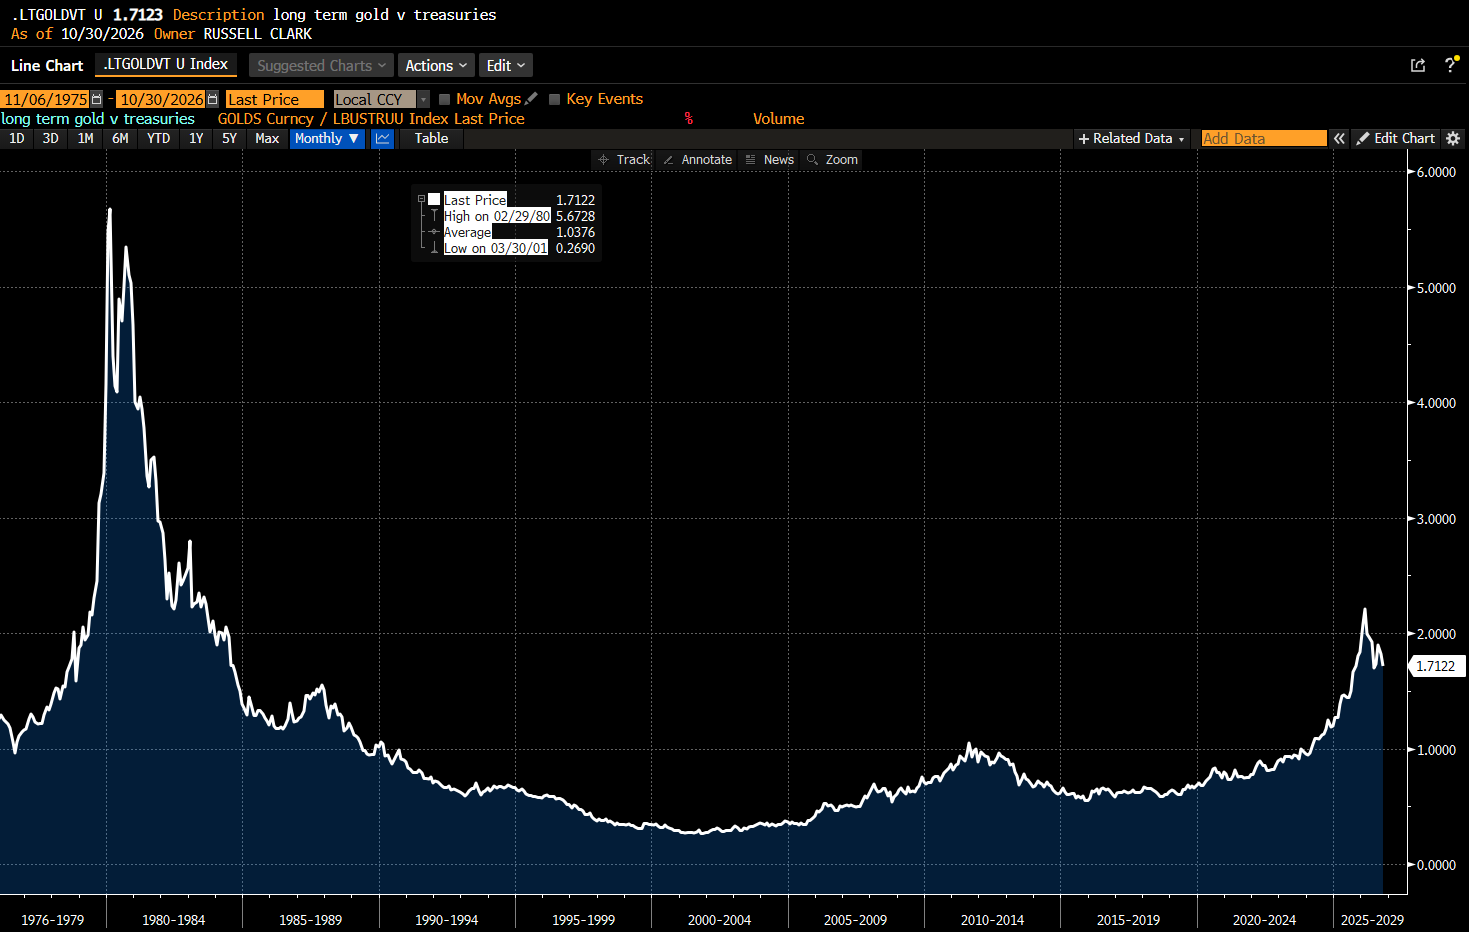
It has returned 500% from 2020, so maybe this trade is done? Using a longer time series, its feels like a correction.
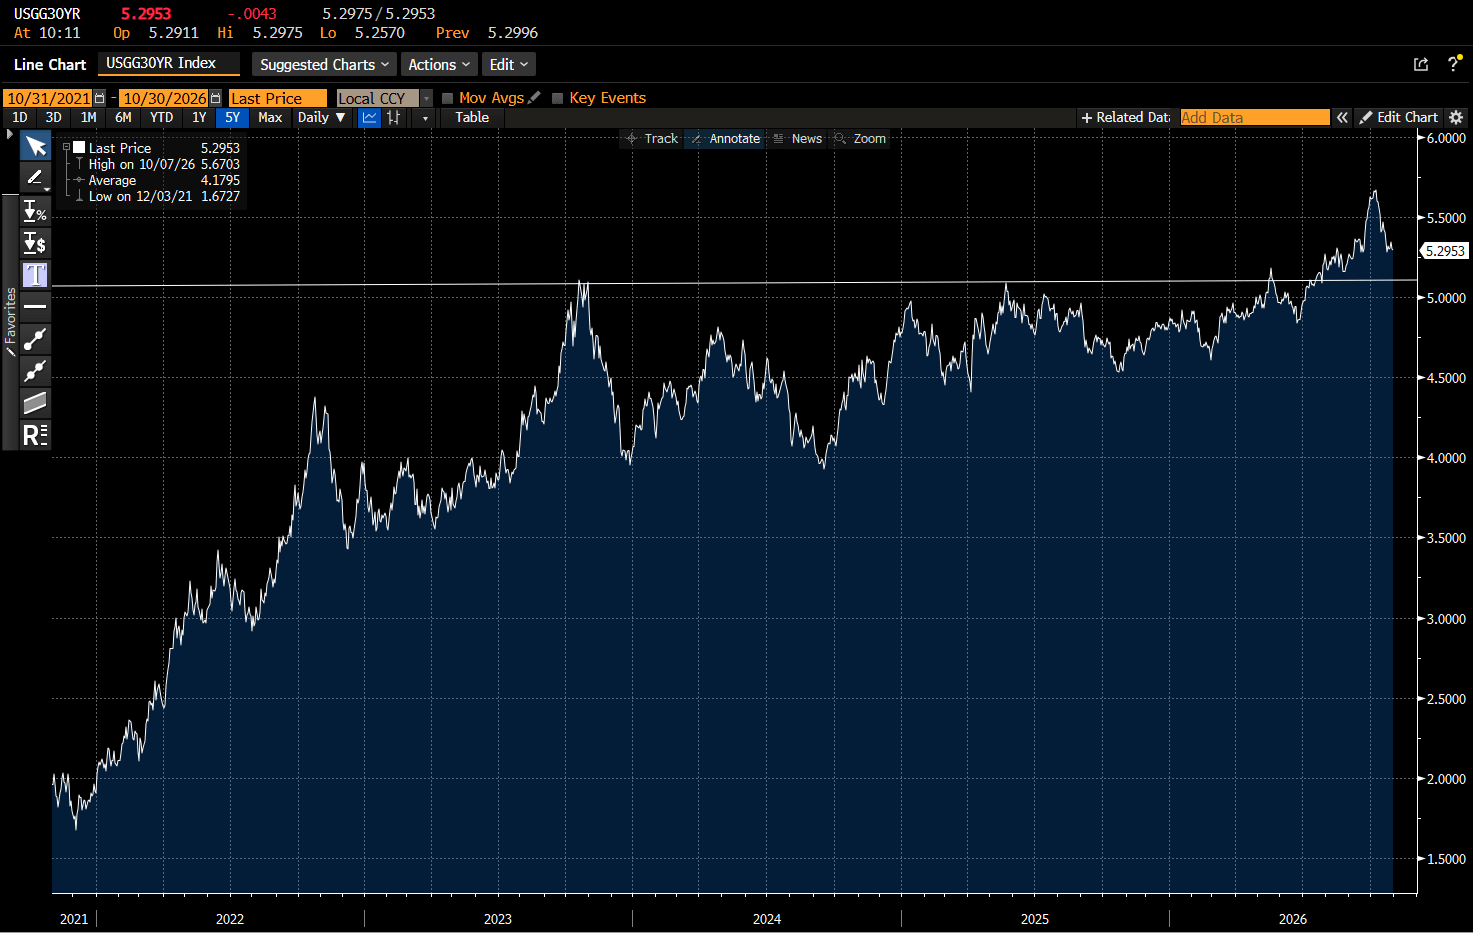
But the point of GLD/TLT is that they should be broadly speaking positive correlated, so when TLT is doing well, GLD should do well and vice versa. And then in the final stage, the correlation breaks down, as a debt crisis in the US causes TLT to tank AND gold to soar. Coming into this month, we saw long dated treasuries break higher to and through 5%, so it seemed the trade was on course, but this month yields have fallen again.
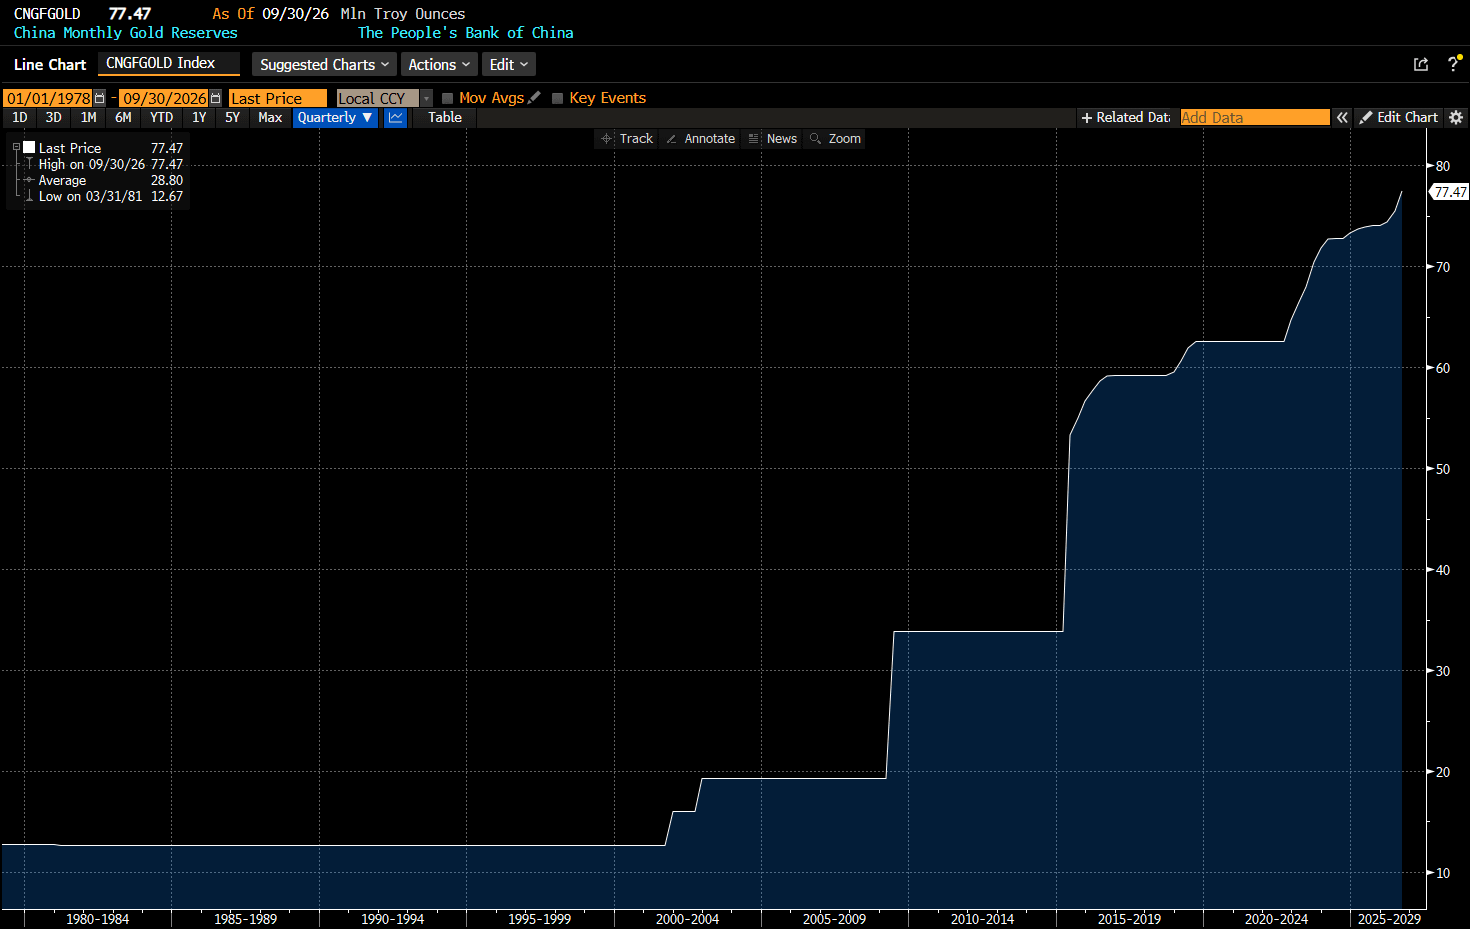
The other political part of GLD/TLT was that with the freezing of Russian foreign reserves, I saw the end of the US treasury as a foreign reserve asset, generally true for everyone, but particularly true for China. Chinese foreign reserve buying of gold continues.
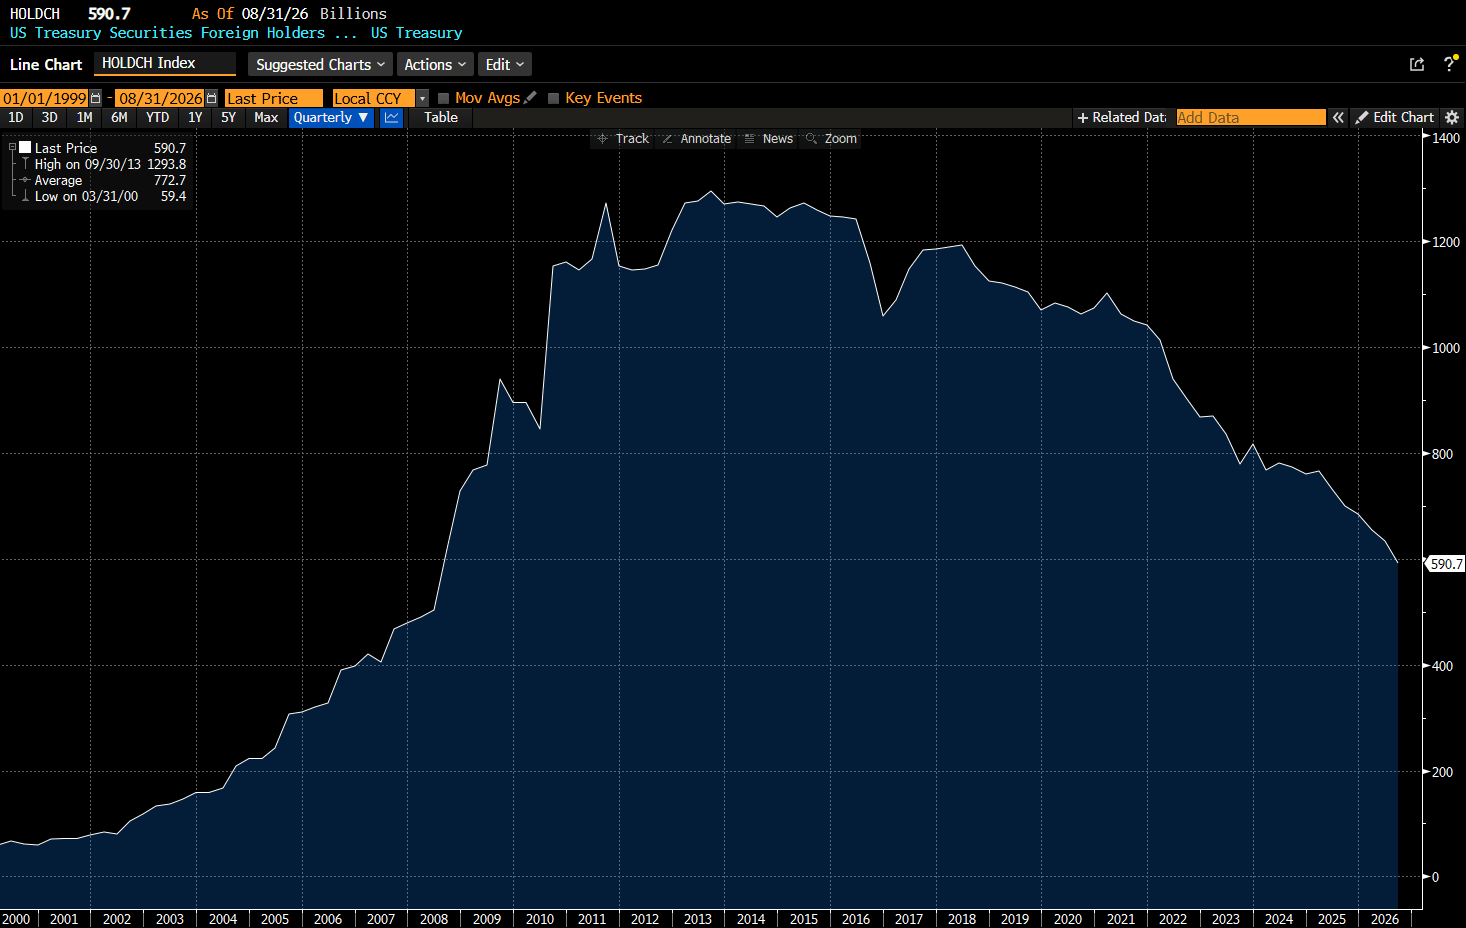
While Chinese holdings of Treasuries continues to fall.
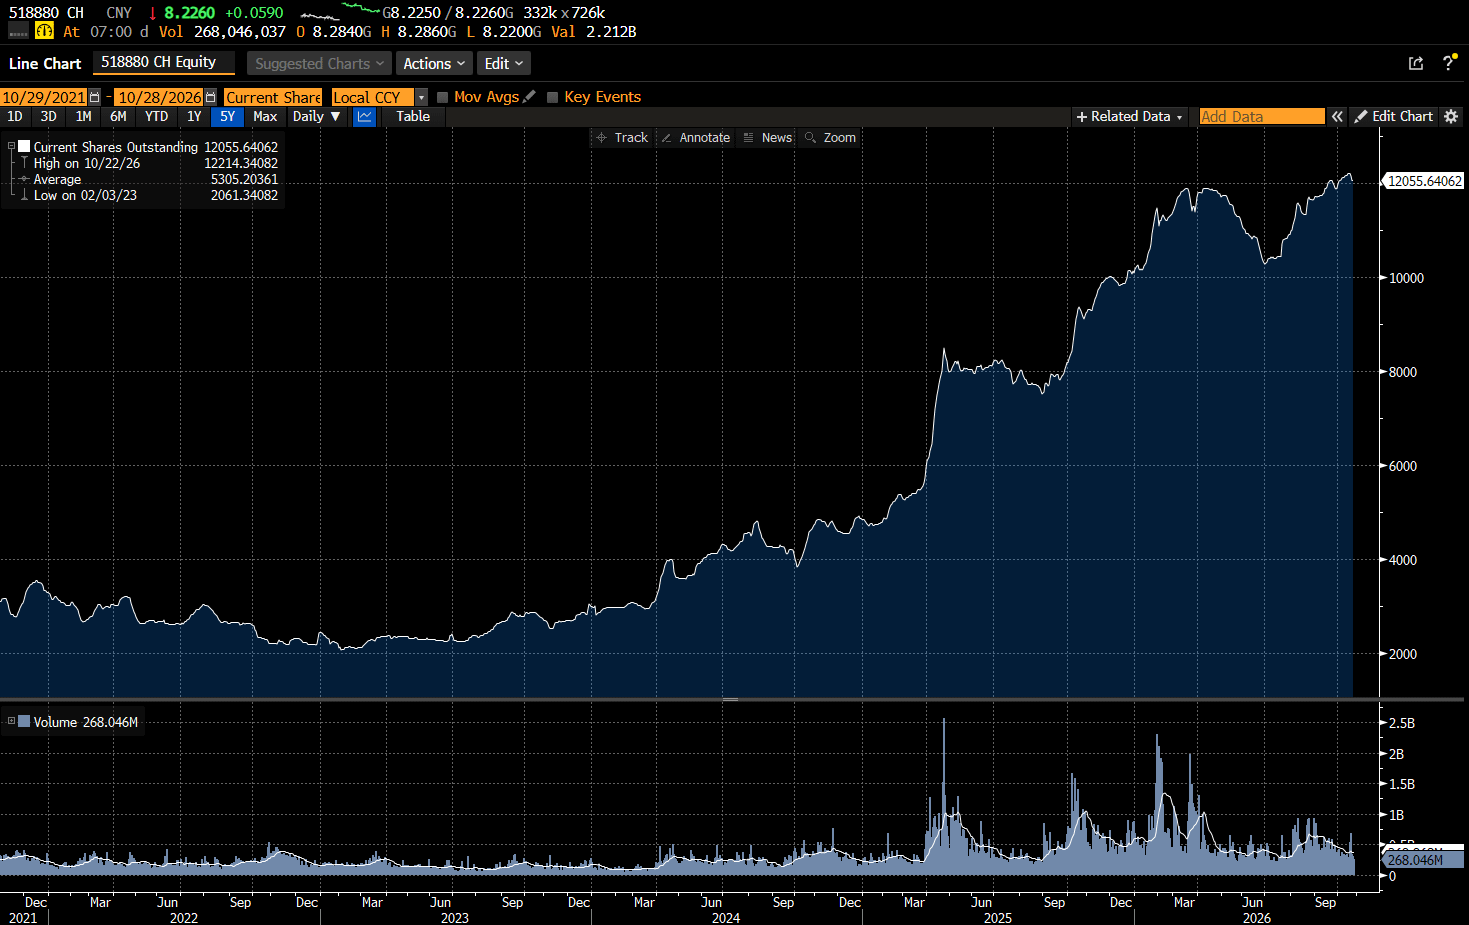
Chinese retail buying of gold remains strong, as proxied by domestic gold ETF shares outstanding.
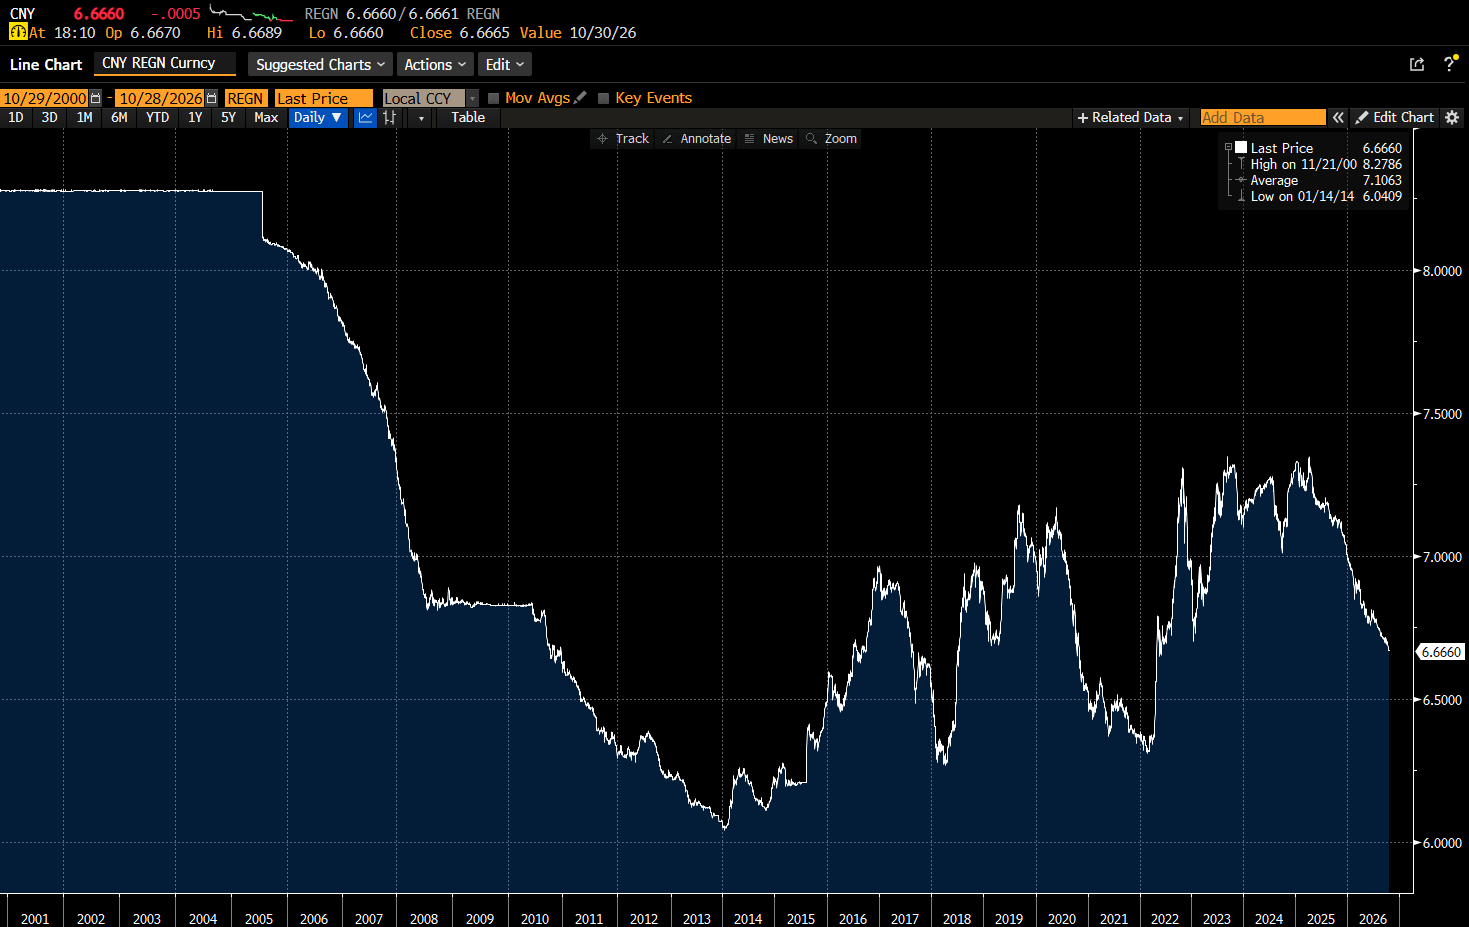
Even more baffling is that the Chinese Yuan has been appreciating, which is generally bullish for gold, and inflationary.
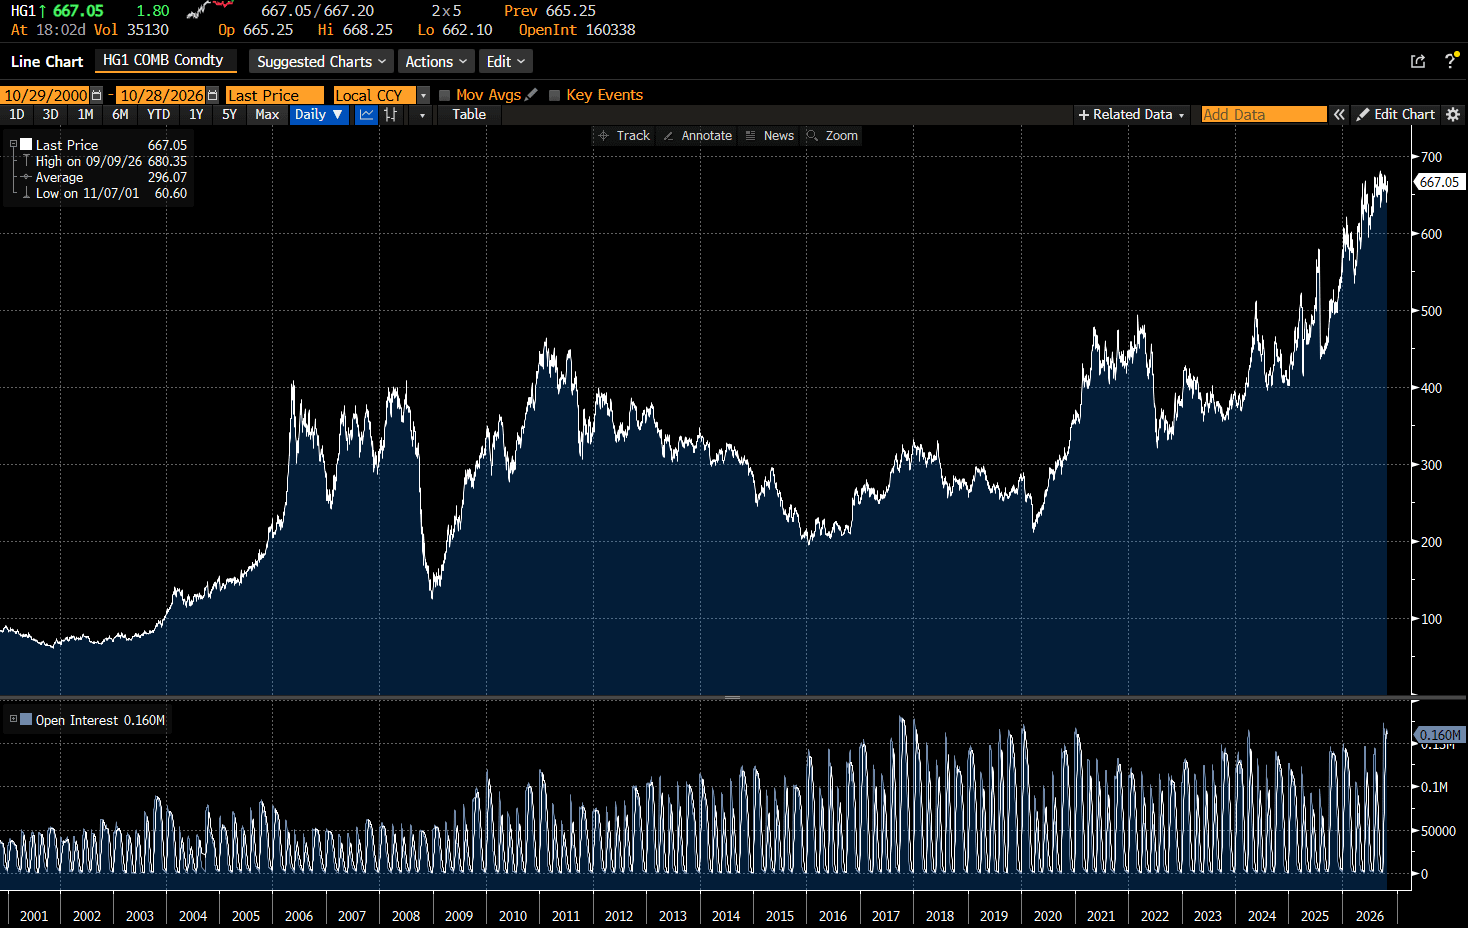
Copper also remains near highs. As a rule of thumb, a weak copper price is not good for gold.
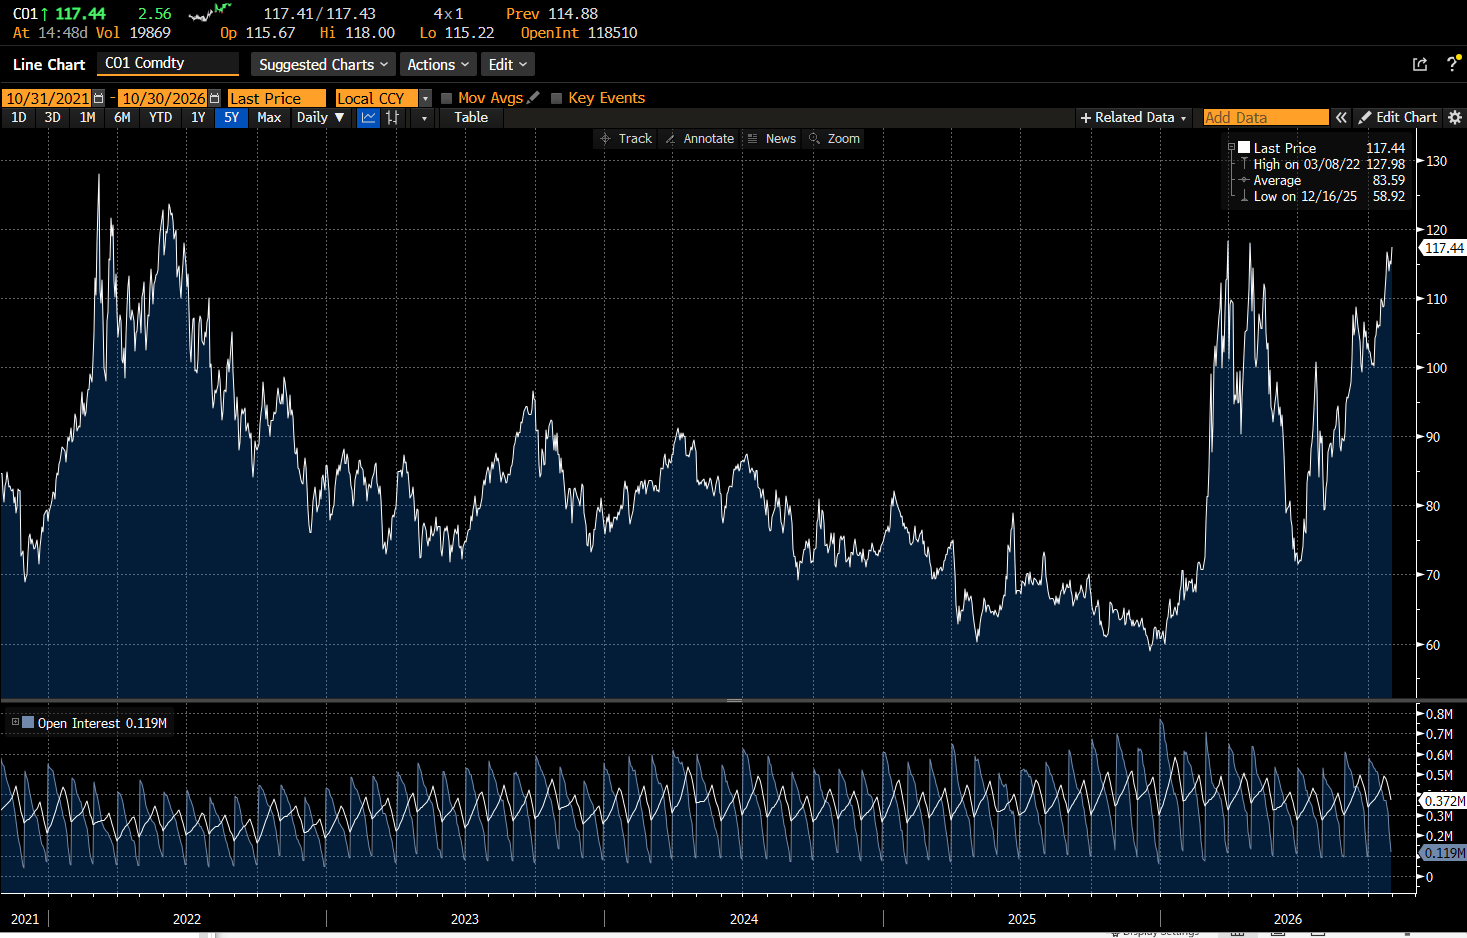
So none of the reason I like GLD/TLT has changed. What has changed this year has been the oil markets. Oil has been volatile ever since the War in Iran started. In some ways, GLD/TLT is trading inversely to the oil market. When oil spikes, GLD/TLT falls.
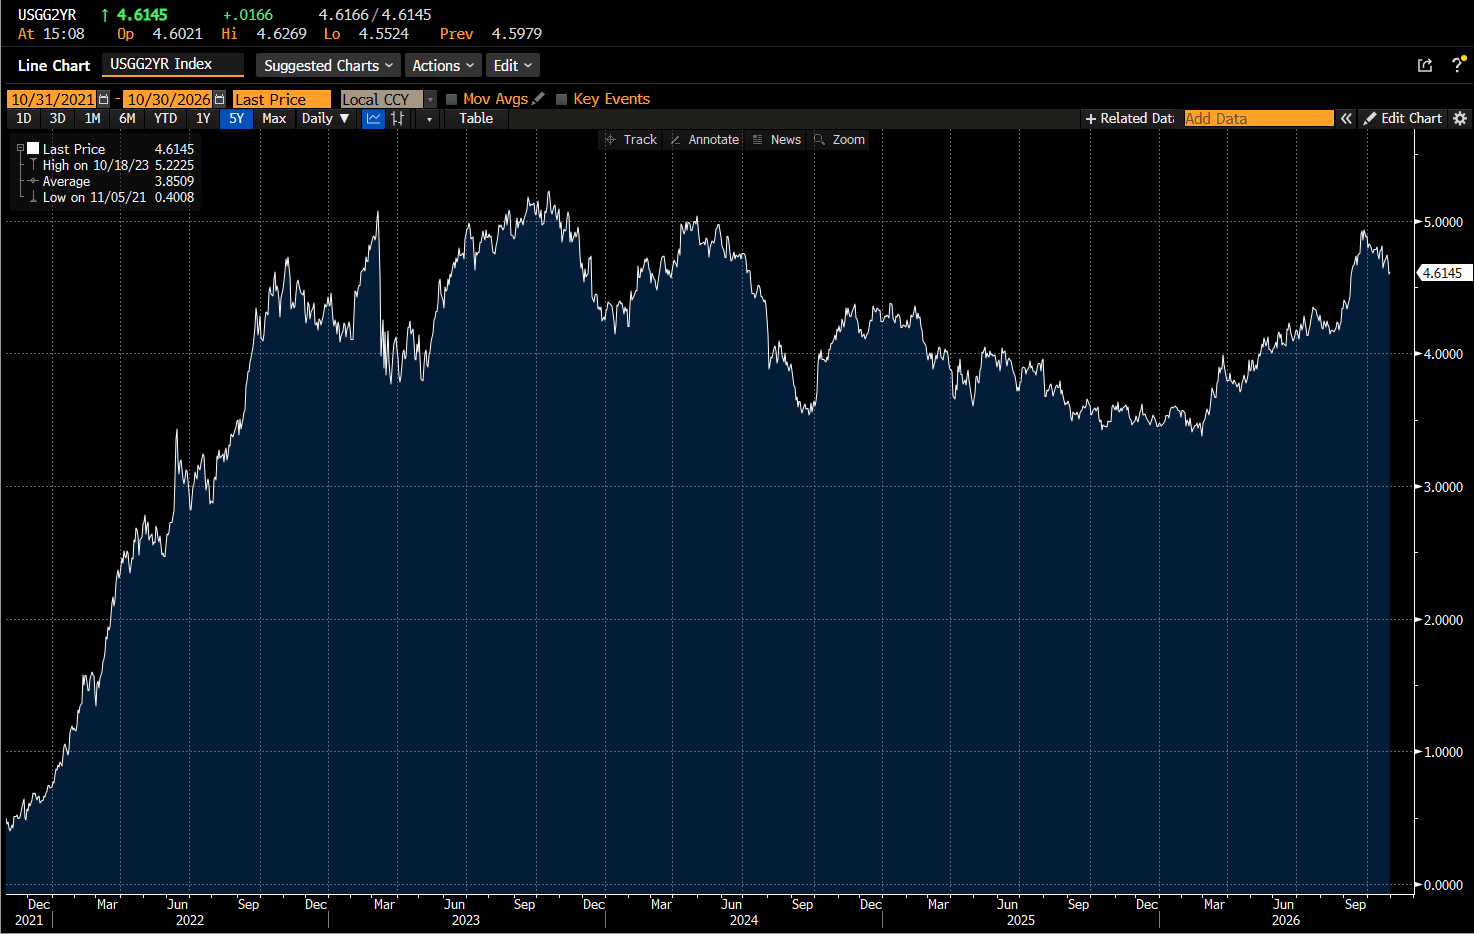
I have a real hard time seeing GLT/TLT as an inverse oil trade. But I can see spiking oil causing the Federal Reserve becoming more likely to raise interest rates. The 2 year US treasury yield has risen a lot this year. That is GLD/TLT does poorly as shorted dated yields rise.
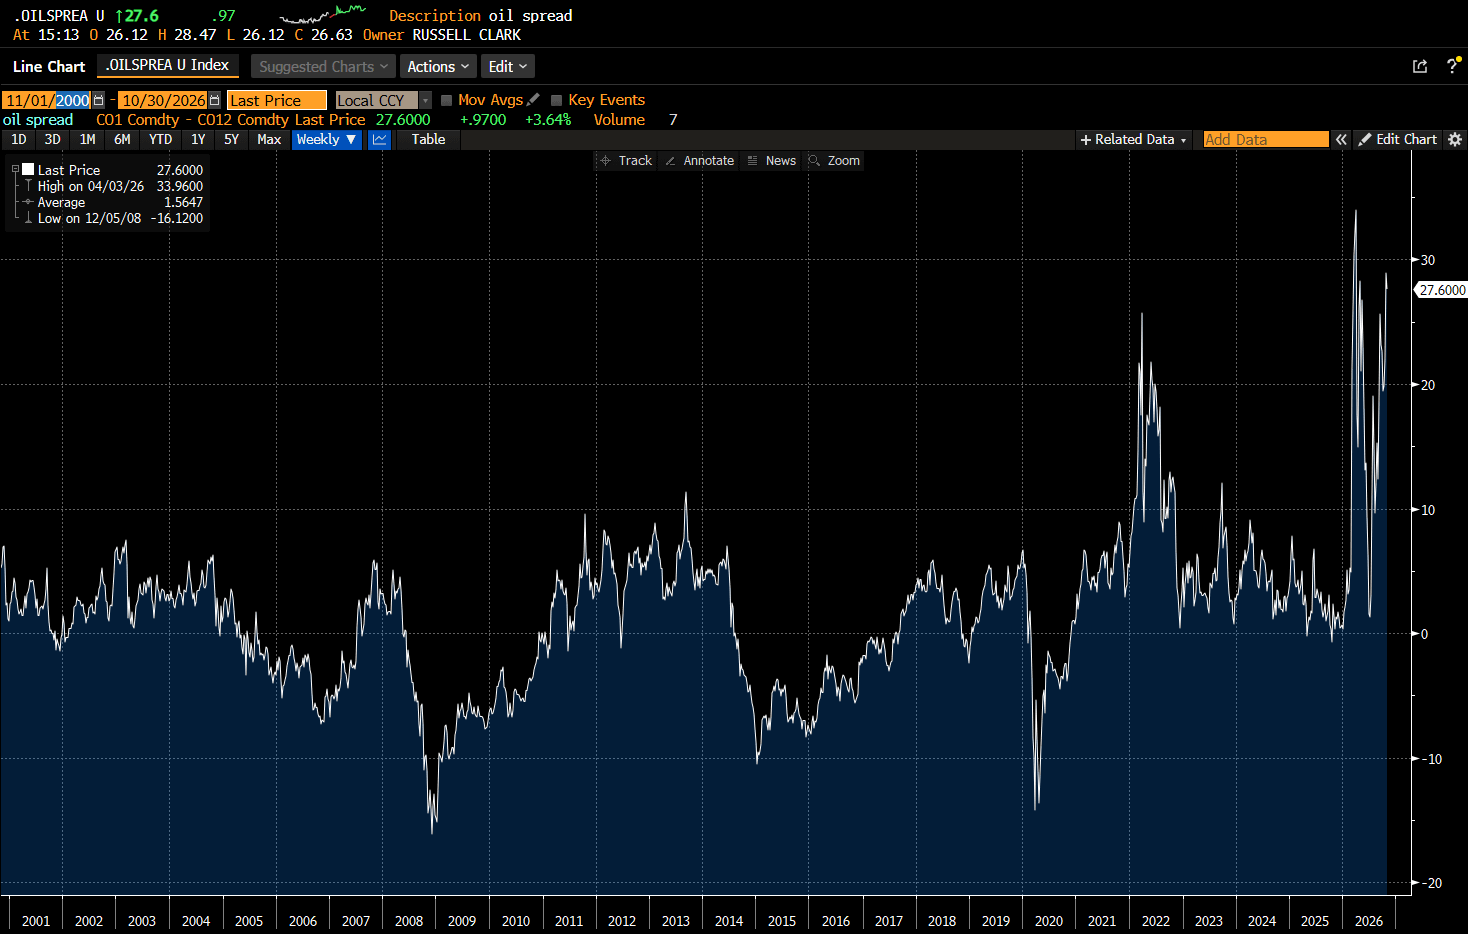
This leaves two options with GLD/TLT - one is to change TLT from long dated to short dated. I don’t like this option, as the short end of the curve is volatile, and does not give me the permanent capital loss of TLT as yields rise. The other option is to change gold to oil. I have been giving this some consideration. The problem is the macro and politics are poor. First, on the macro, the spot spread to 12 month future is already at a point that makes buying oil risky.
Secondly, a supply response is already visible. After years of consolidation, the US shale drillers are getting back to work.
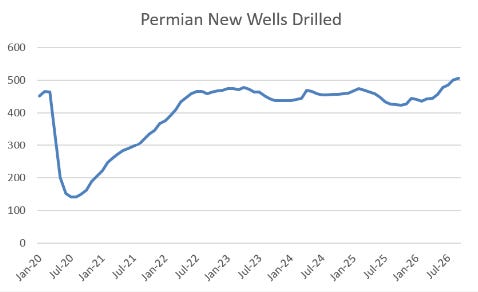
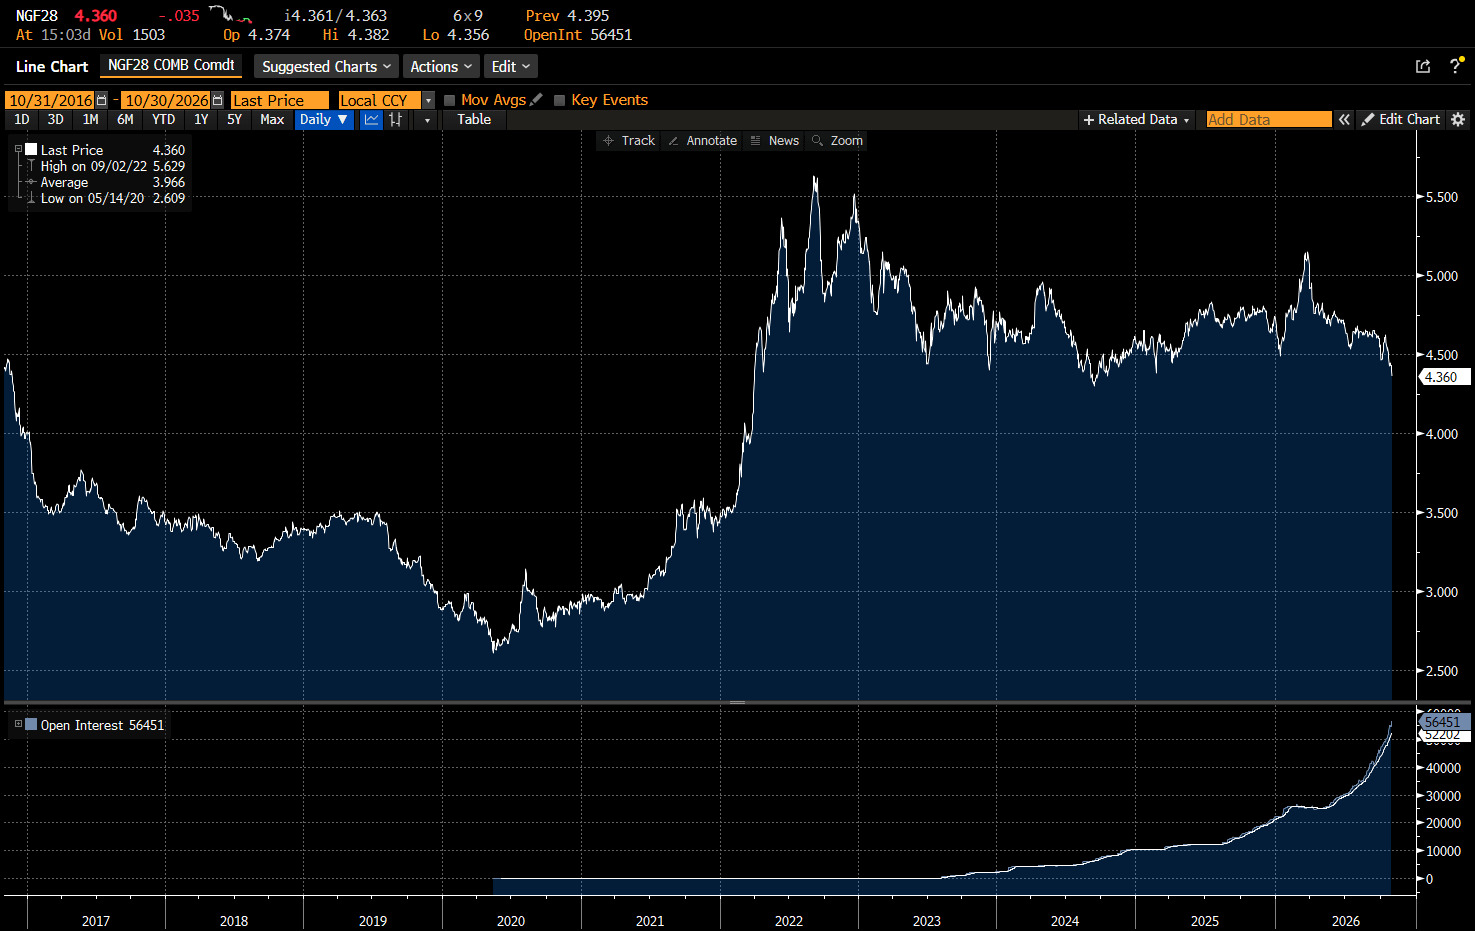
US Natural Gas futures are already responding to this increased supply. January 2028 NG futures are at the lowest level for some time. If I am going to chase energy stocks, I am not going to do it as US supply starts to increase.
Finally the politics of oil is ugly. High oil prices hurts China more than the US, so the pressure for some sort of Iran/China deal is likely. Even without a deal, reports of 80% of the flow being restored abound. The risk with chasing oil here is some deal gets done, and you are offside immediately. This is the big problem with all the trades that the market is trying to push me into - the politics looks wrong. Buying sovereign bonds when both left and right wing populists are making the running? Short AI, just when governments are perceiving it as a strategic asset? Sell gold to buy treasuries even as the US is probably losing Middle Easter buyers of treasuries as a reserve asset? What WOULD get me bearish on GLD/TLT would be a decisive turn in 30 Year JGB yields. They are sitting on the 200MDA.
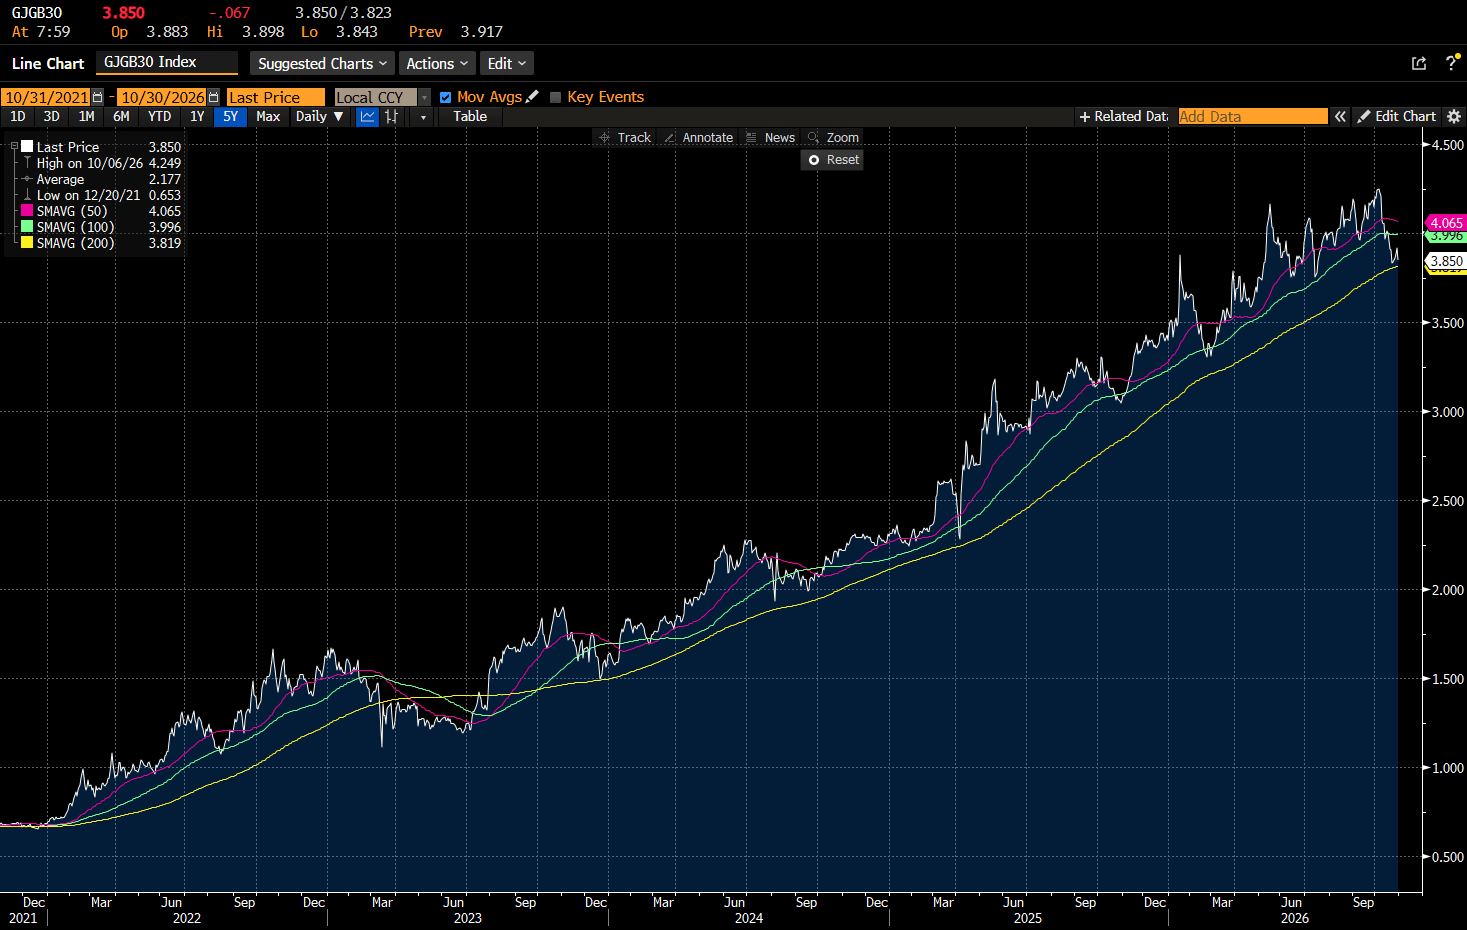
The Japanese know about deflation. If they say deflation, then I believe them. JGBs still say inflation. What I think markets are saying is we have finally come to the pinch point in bond yields, where lending to the government looks more attractive to lending to corporates. But if my read of politics is correct, we will likely see governments lend to corporates soon enough.
For those of you not used to my style of thinking, I would call this a model test. I have a way of thinking about the world, and pro-labour, rising yield theory would say, this is a de-grossing event, to be bought. And the macro, financial theory of the world would say this dot-com bust all over again. The political analysis says the former - but JGBs told me when to put his trade on, and they will tell me when to take it off. Right now they say wait.


