
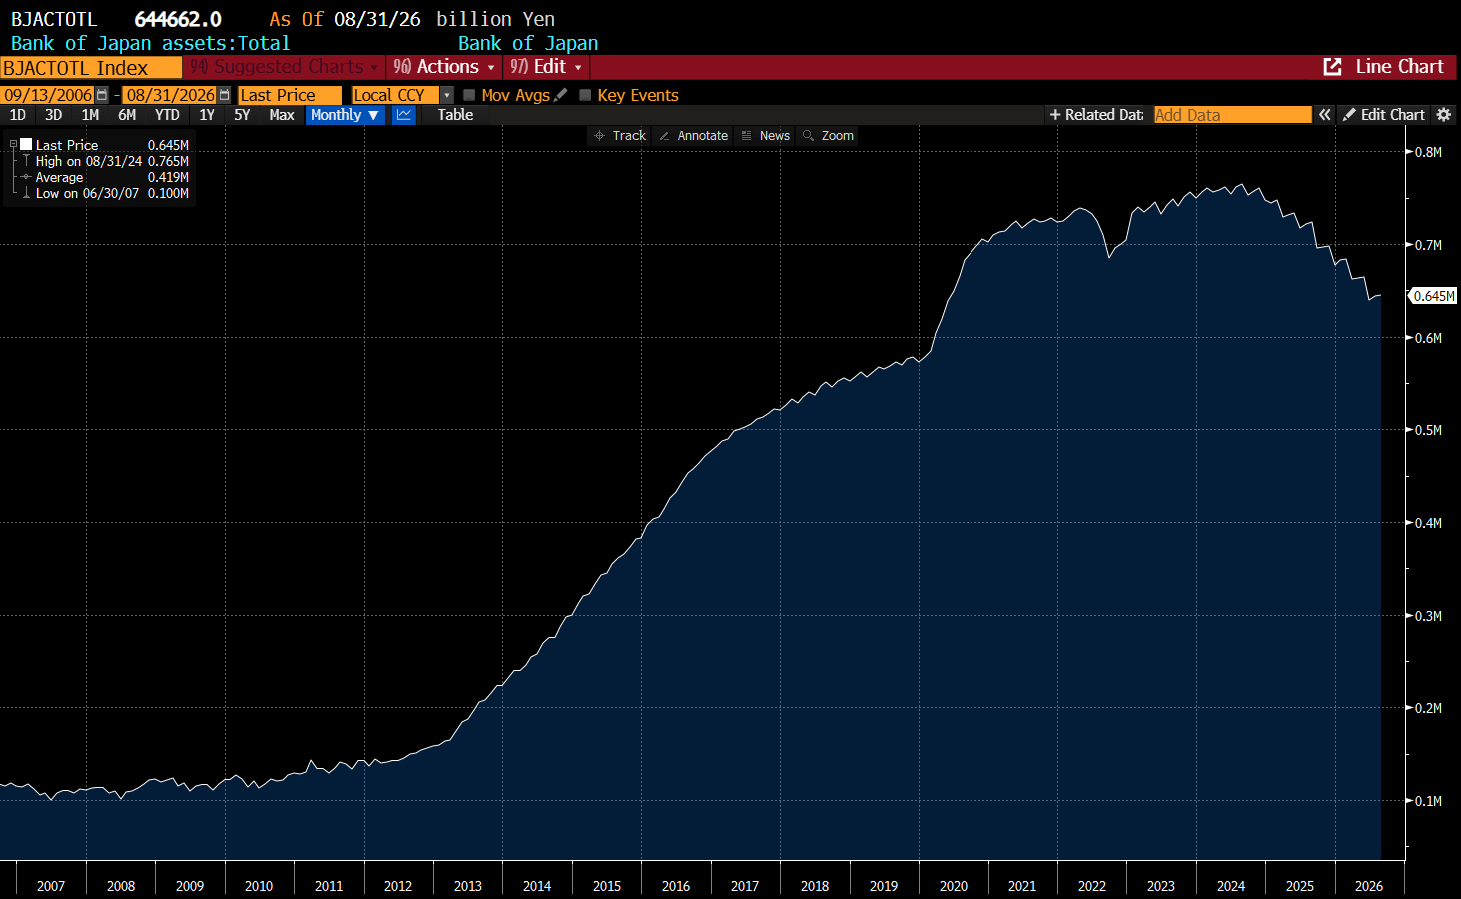
One of Prime Minister Abe’s aim was to get Japanese investors to stop being conservative. He was particularly keen on getting Japanese investors out of JGBs. The main was was to get the Bank of Japan buying basically the entire JGB market. In USD terms, the BOJ balance sheet went from USD 1.7tn to about USD 7tn
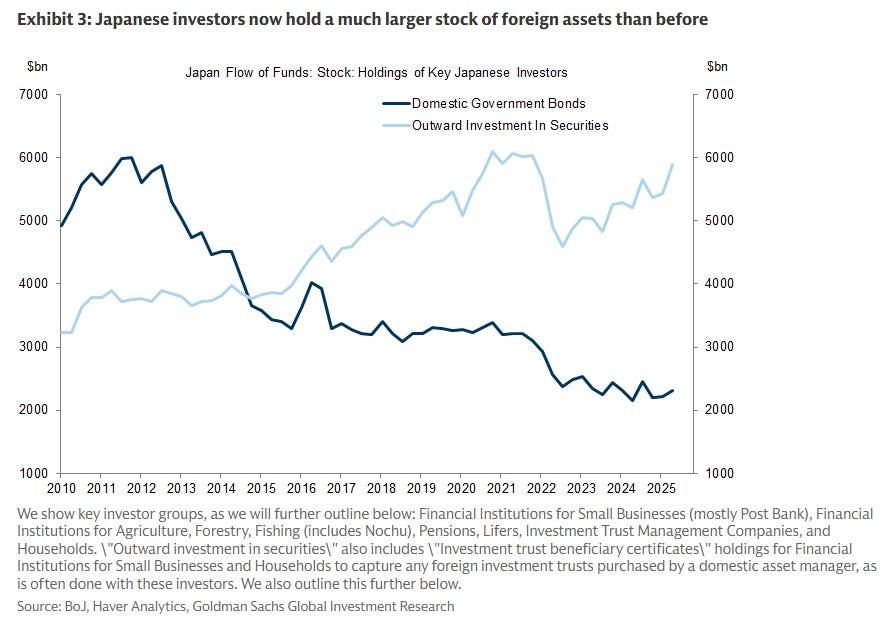
And this has led to Japanese investments in domestic bonds falling dramatically. In other words the BOJ bought bonds of JGB investors at a very high price.
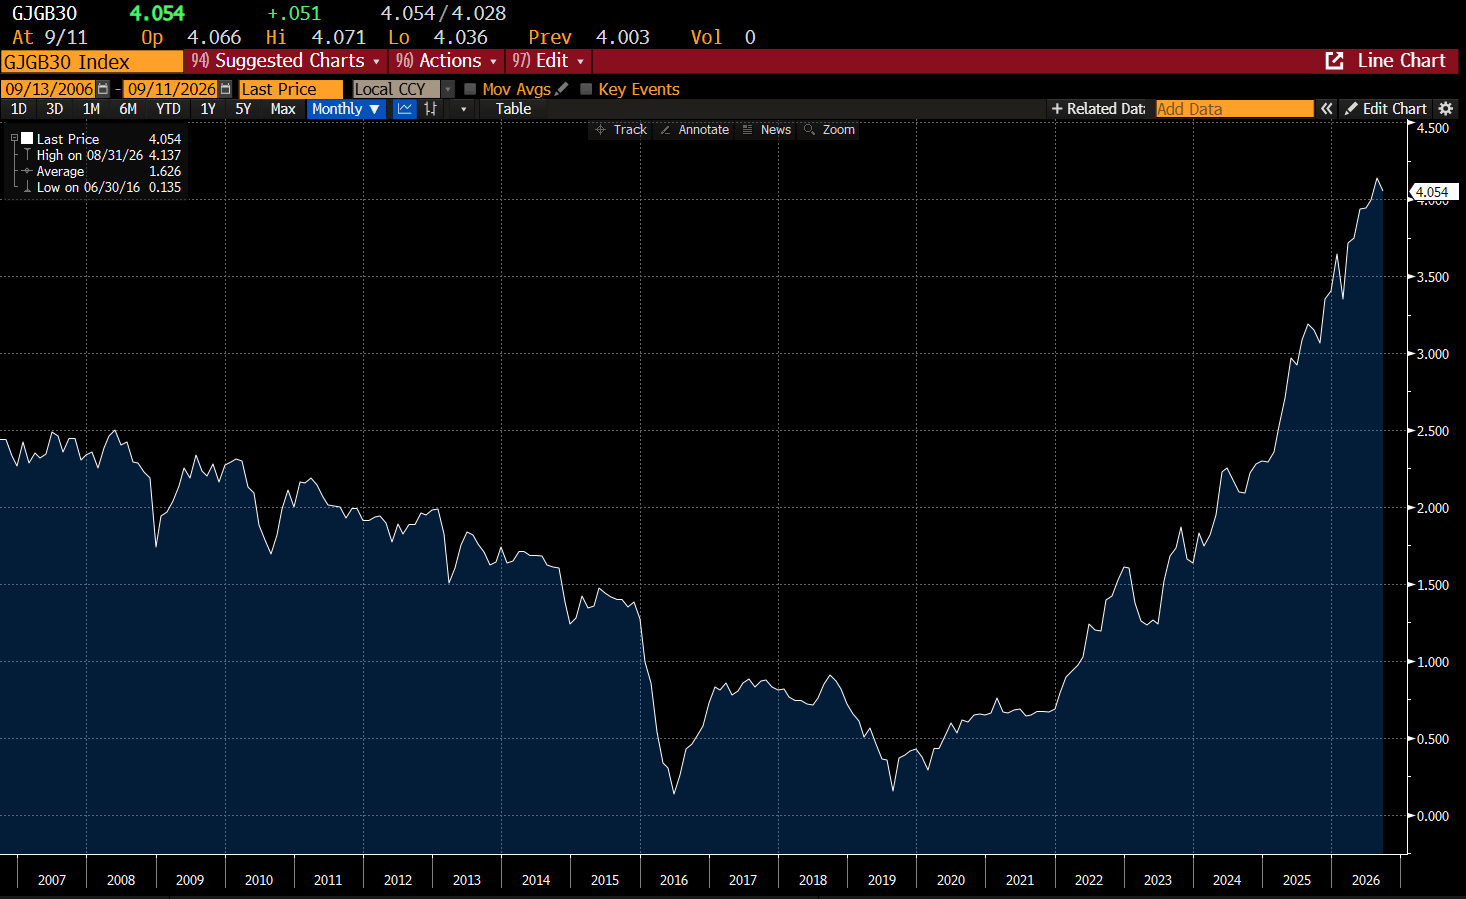
The good news for Japanese investors is that they sold most of their JGB holdings before yields rose. Or if you are more cynically minded, Japanese banks saw what was coming and dumped their holdings on the BOJ. Long dated yields in Japan have surged in recent years (bond values have fallen).
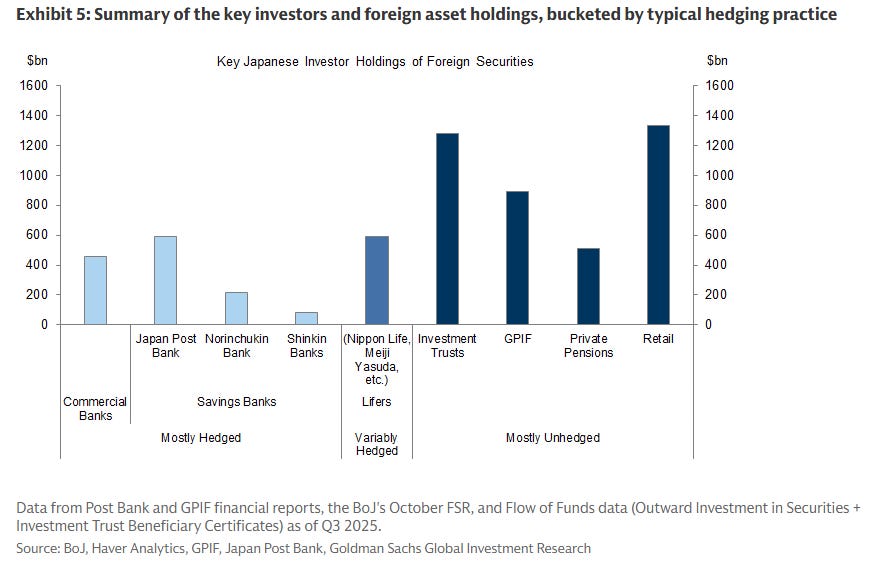
But as the graph earlier pointed out, Japanese investors have not sold their foreign debt holdings. As GS point out, the largest holdings are now held by investors that do not hedge (there are good technical reasons for this). But basically, Japanese have large UNHEDGED fixed income positions.
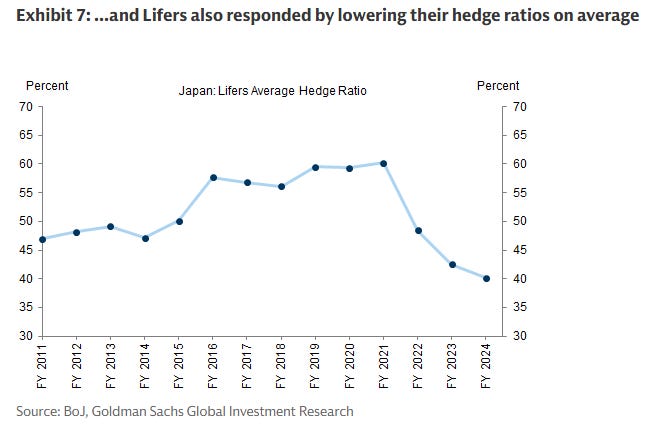
Even life insurers, who usually hedge their portfolios - they have let hedging ratios fall a long way.
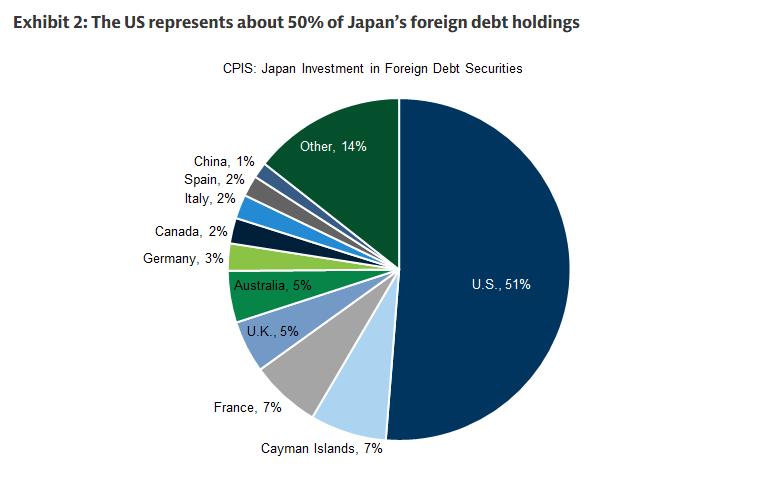
Over half of their foreign holdings are in the US.
Anyway you cut it, Japanese investors (pension funds, retail and insurers) have a large unhedged position in US Treasuries. This might seem odd - TLT US - which gives a good guide to the capital value of US treasuries has been very poor.
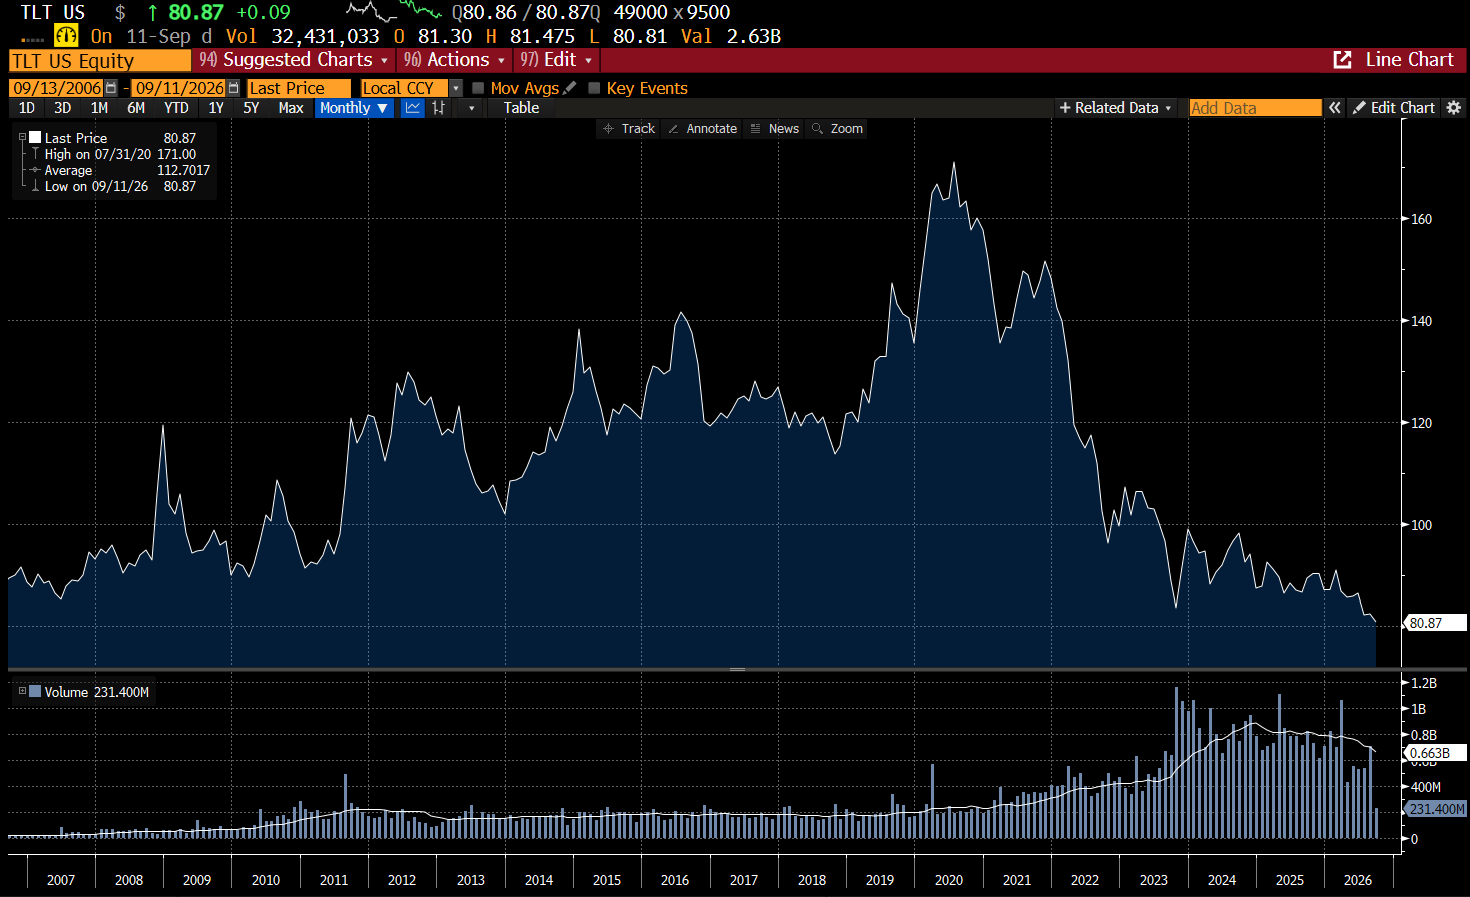
But in Yen terms, it has been fine (ish).
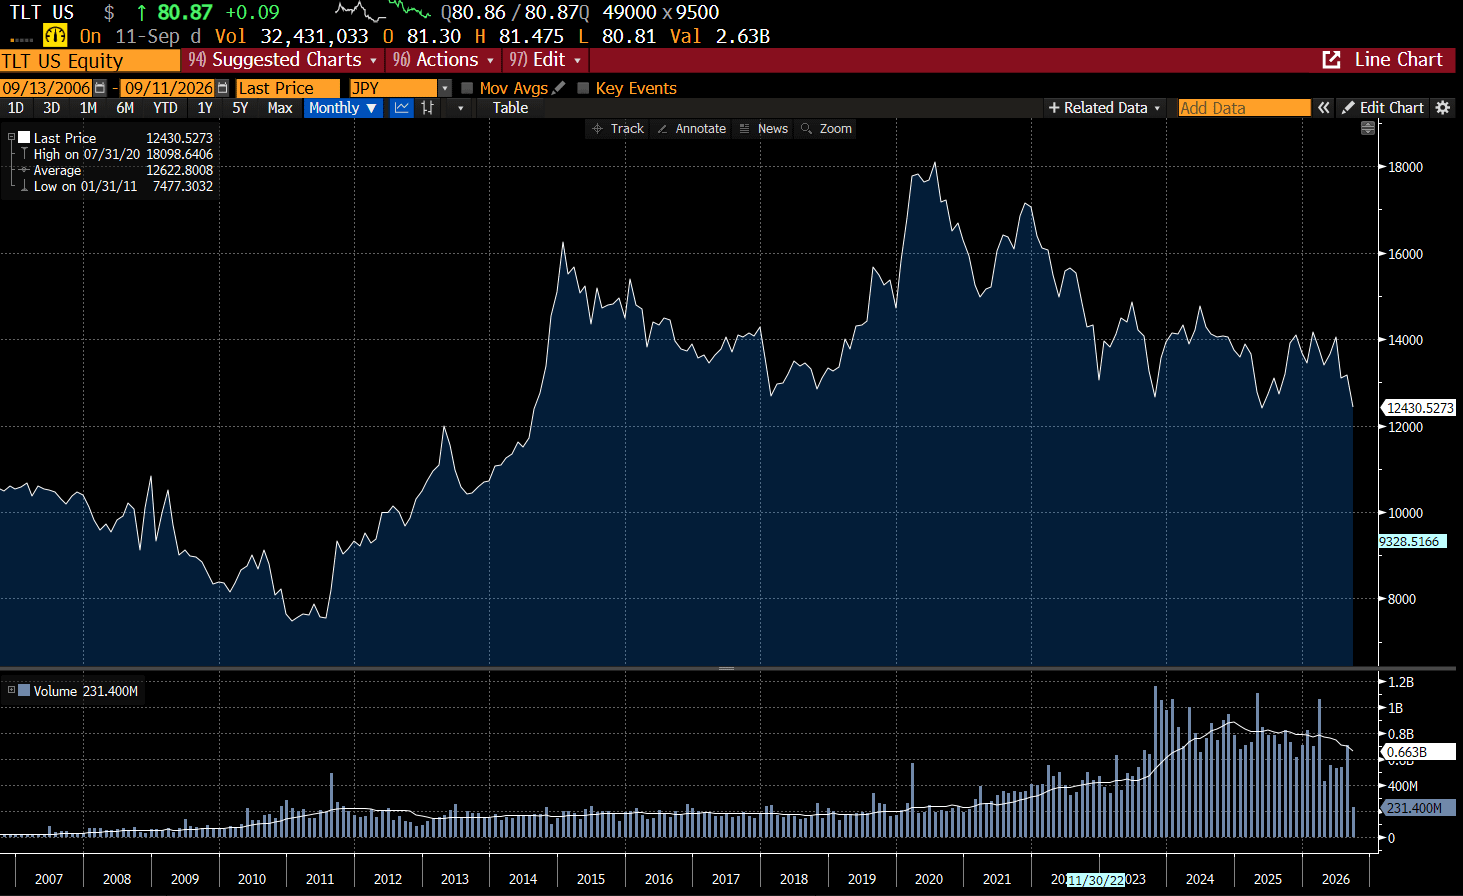
This is particularly true when compared to a 10yr JGB return index.
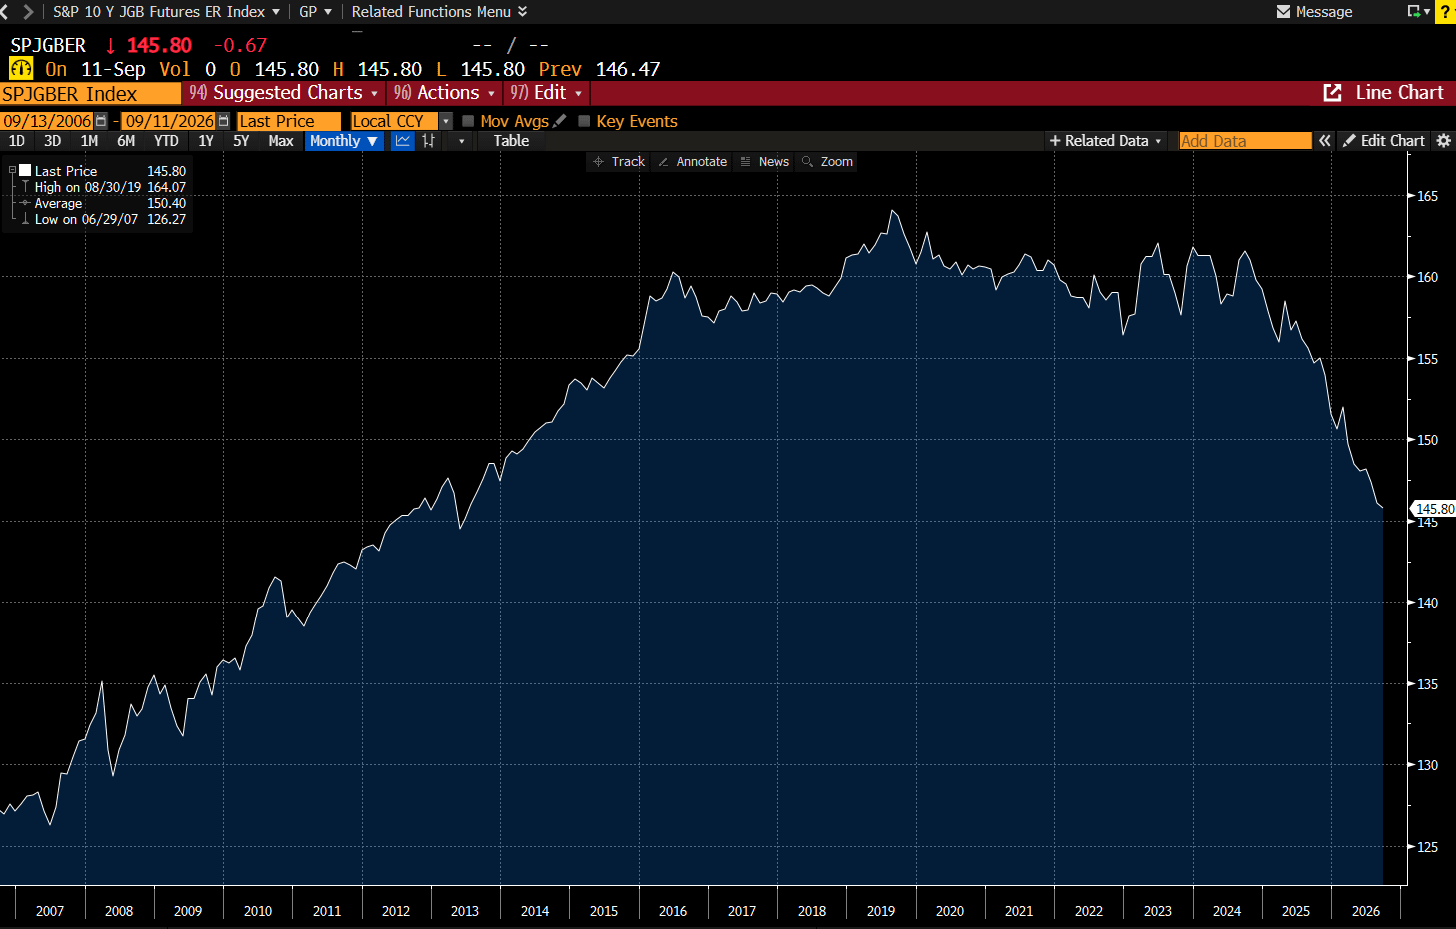
In the old “free market” days of 2016, this combination of very unhedged positioning in the USD assets would make me EXTREMELY bullish on the Yen. Covering the unhedged position would drive Yen higher, which would cause more covering and so on and so forth. Of course the problem with that outcome is that it would drive investors back into JGBs - the very thing they have been trying to stop. But maybe Japanese investors just stop allocating money to US treasuries? US 30 Year Yields are at new highs.
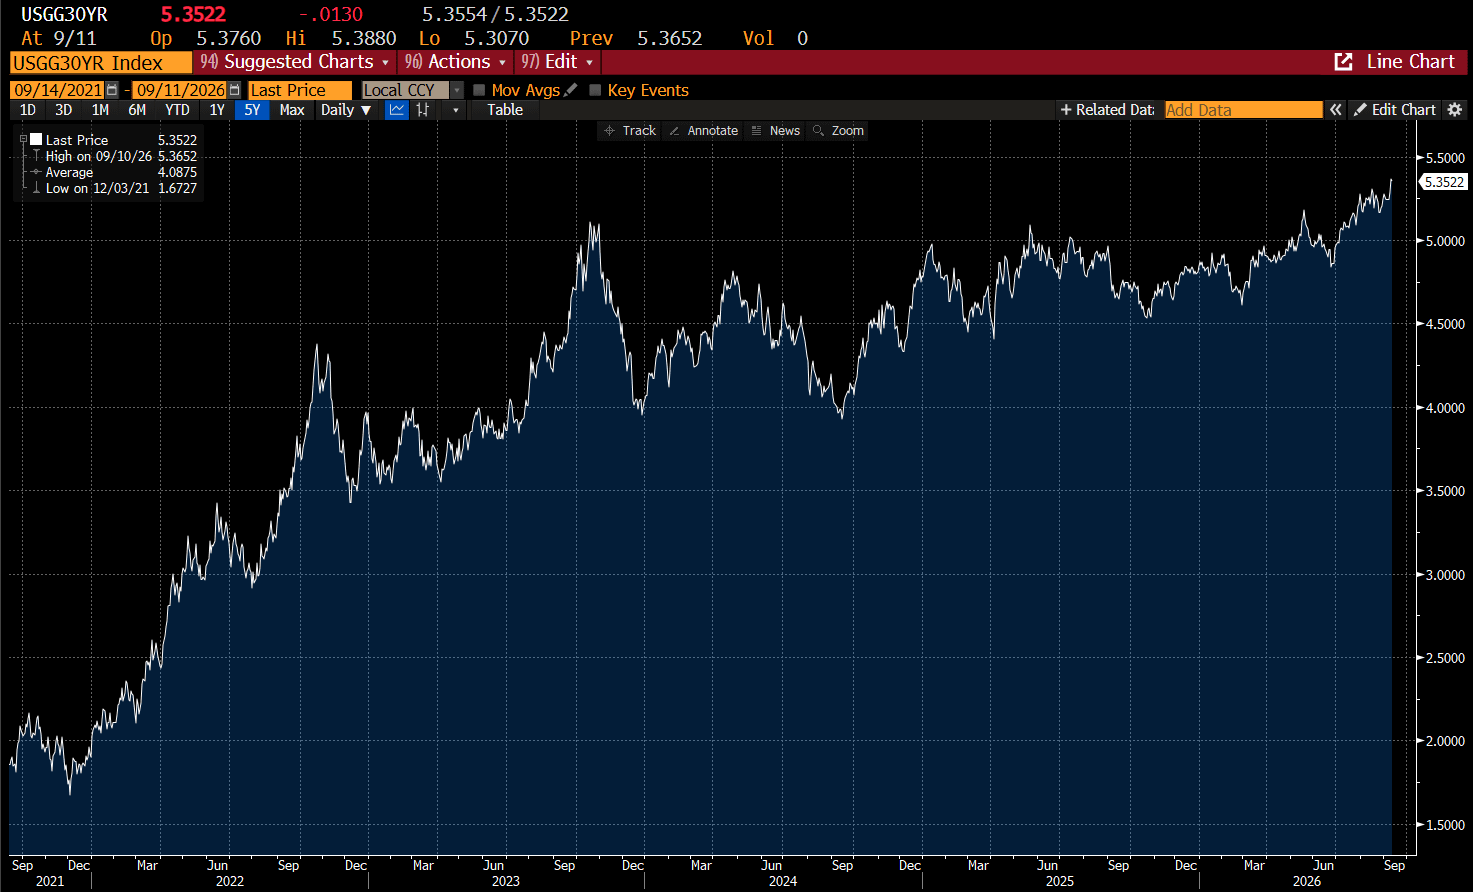
But the Japanese would probably feel a bit miffed that the US is suddenly forcing the Yen higher, after they have loyally helped the US finance its budget deficit. What would I do to try and mollify miffed Japanese investors? I would probably announce a buy back (bit like the BOJ and its QE to help them out of JGBs), to support the market as Japanese try and sell. The treasury has already upped the buyback once. The next step will be to make the buyback big enough for Japanese investors to sell into. What sort of numbers would that be? Lets say US 4 trillion total investment by the Japanese. The total treasury buy back is currently USD 65bn a quarter. To help out the Japanese, it probably needs to be USD 200bn a quarter. I expect the buy back to be increased.


